At the Martinez family’s glittering Christmas gathering, Daniel is dismissed by his wealthy uncle as a directionless day trader, unaware that Daniel manages more than a billion dollars. When Daniel discovers that his uncle’s celebrated investment firm is taking reckless risks, he orders a $287 million withdrawal.
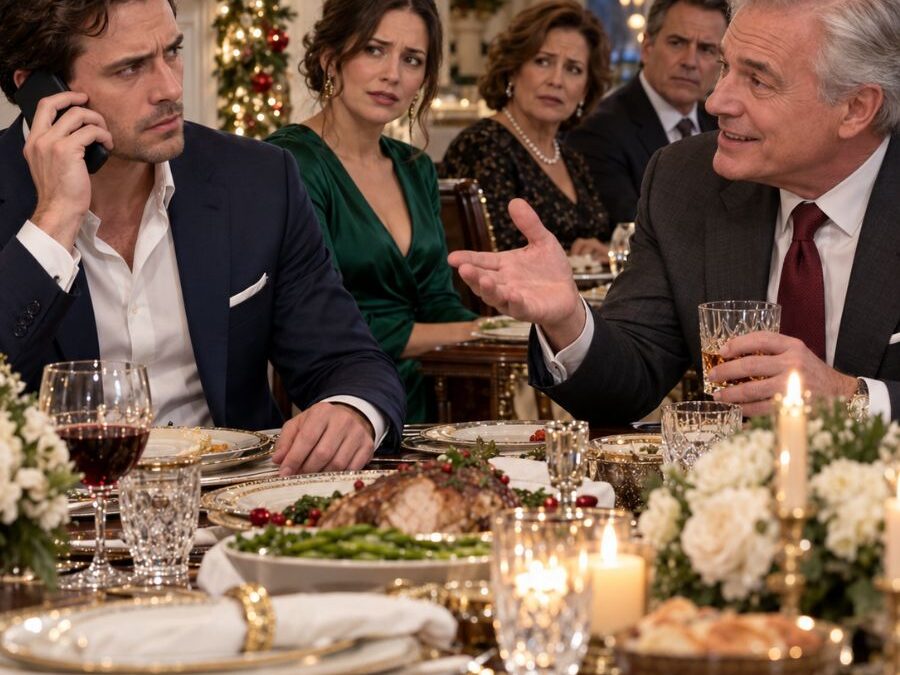
At the Martinez family’s glittering Christmas gathering, Daniel is dismissed by his wealthy uncle as a directionless day trader, unaware that Daniel manages more than a billion dollars. When Daniel discovers that his uncle’s celebrated investment firm is taking reckless risks, he orders a $287 million withdrawal. The decision threatens the firm, ignites a family feud, and exposes years of painful assumptions. But the real test comes after the market turns, when apologies, renewed trust, and a secret reinvestment reveal whether success is measured by status—or by the discipline to protect what matters, even when nobody applauds him.
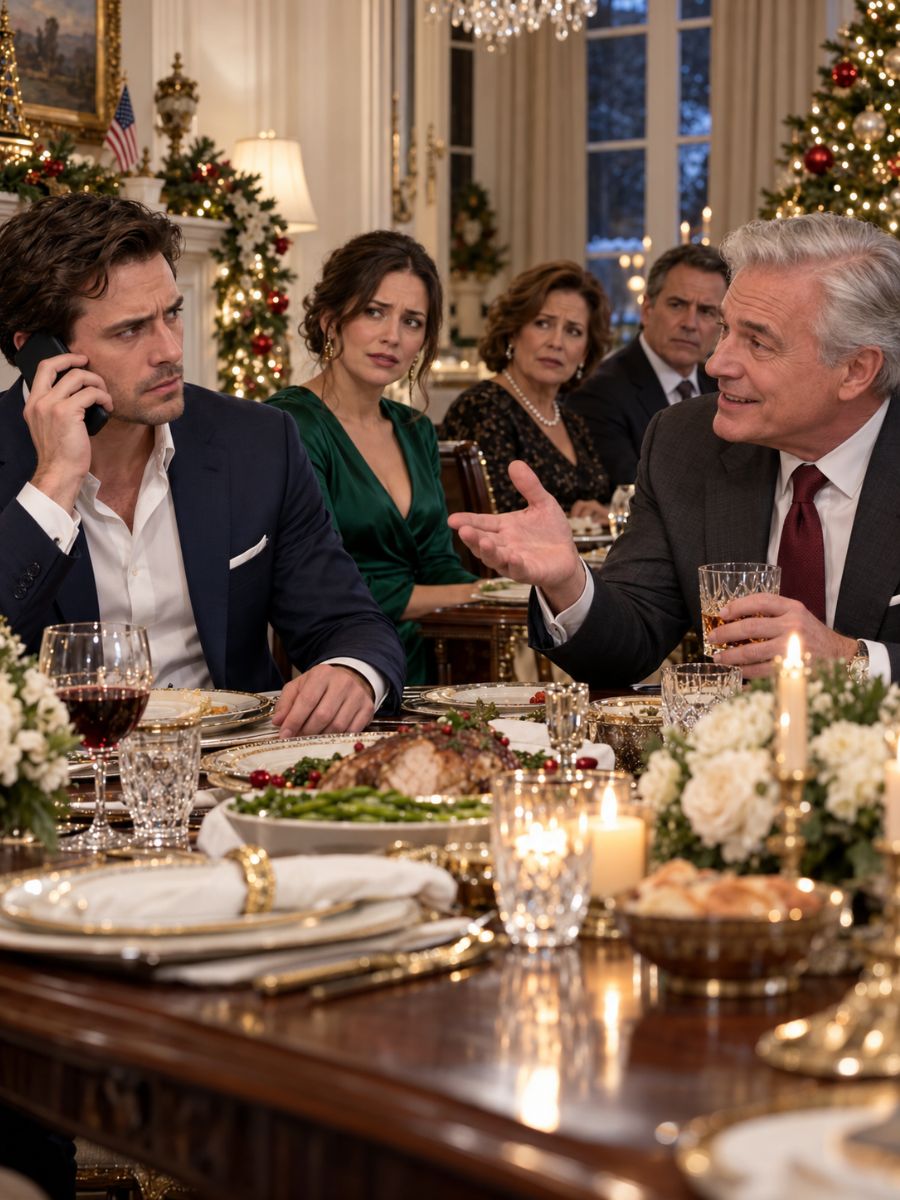
Part 1: My Uncle Mocked My Career at Christmas While Hiding From the Truth.
The Martinez family Christmas was held at my Uncle James’s sprawling estate in Greenwich, Connecticut, where success was measured by the size of your yacht, the school your children attended, and the number of people who stood when you entered a room. That evening, I sat alone on a leather couch in his home office, reviewing market data on my laptop while expensive champagne flowed in the main house.
Outside the tall windows, snow dusted the manicured lawn. Inside, relatives laughed beneath crystal chandeliers, comparing vacation homes and business acquisitions. I could hear every boast through the partially open door. I had learned long ago that the easiest way to survive a Martinez family gathering was to find a quiet corner and let everyone underestimate me.
Then Uncle James walked in.
He wore a Brioni suit that probably cost more than some people’s monthly salaries. A glass of scotch rested in his hand, and his expression carried the familiar confidence of a man who believed every room belonged to him.
“Still glued to that computer?” he asked. “Daniel, it’s Christmas. Can’t you take a break from whatever you’re doing?”
“Just reviewing a few positions,” I answered.
He laughed and settled into his desk chair.
“Positions? You mean your little stock portfolio? You’re thirty-six years old. When are you going to get a real job instead of playing with stocks in your apartment?”
I lowered my laptop slightly. My first instinct was to defend myself, but I stopped. Arguing with someone who had already decided you were a failure was exhausting.
“I do okay,” I said.
“Okay?” He shook his head. “I’ve spent thirty-five years in finance. I run a private equity firm with $2.8 billion in assets under management. I know what success looks like, and sitting around day trading isn’t it.”
“I don’t use E*TRADE,” I replied.
He waved dismissively.
“Whatever platform you use, it isn’t the same as professional investing. You need structure. Mentorship. A real career path.”
Then came the offer.
He could arrange an entry-level analyst position at Martinez Capital Partners. Nothing prestigious, he explained, but it would give me a start. He spoke as though he were offering a lifeline to someone standing at the edge of financial ruin.
“I’m family,” he added. “Your father would have wanted you to have a proper career instead of turning a day-trading hobby into your entire life.”
That sentence hurt more than the others.
My father had been gone for seven years. He had left me $200,000, and James assumed I was still stretching that inheritance through careful budgeting and occasional lucky trades. He had never asked what I had built with it. I had never volunteered the answer.
“The market’s been good to me,” I said.
“This bull market has been good to everyone. When it turns, amateurs get burned.”
He began describing MCP’s due-diligence procedures, research teams, and sophisticated risk-management systems. He boasted about the firm’s twelve-percent annual returns over the previous five years.
I listened quietly.
I knew those returns intimately. I also knew something about the firm that my uncle apparently didn’t want to consider: its risk profile had begun to deteriorate.
My phone vibrated.
The message was from Sarah Chen, my chief financial officer.
Need to discuss the MCP position. Call when you can.
I silenced the screen.
James noticed.
“That’s exactly what I’m talking about. You’re constantly checking prices. That’s speculation, Daniel. Professionals establish a strategy and stick to it.”
I nodded, allowing him to continue.
He complained about my seven-year-old Honda Accord, my modest Stamford apartment, and the fact that I didn’t have an employer providing my benefits. Then he compared me with my cousins. Eduardo earned $400,000 at Goldman Sachs. Maria managed a $600 million hedge fund.
“And then there’s you,” he said. “Honestly, it’s embarrassing for the family.”
“Embarrassing for whom?” I asked.
“For the Martinez name.”
I looked down at my laptop. My hands remained steady, but something inside me had gone cold.
A second message arrived from Sarah.
Urgent. We need to discuss MCP’s Asian expansion.
I stood.
“Work call.”
James laughed. “Work? Fine. Think about the offer. I’ll get you an interview after the holidays.”
I stepped onto the terrace and called Sarah. The cold air sharpened my thoughts.
“MCP published its year-end letter,” she said. “James is celebrating the twelve-percent returns and announcing a major expansion into Asian markets. But the risk metrics are deteriorating. They’re borrowing aggressively to fund acquisitions in markets they barely understand.”
“How bad?”
“Potentially catastrophic. If those markets correct, MCP could lose forty to fifty percent of its capital.”
I stared at the Christmas lights across the lawn.
“Pull out,” I said.
“All of it? Daniel, that’s $287 million. You’re their largest investor. A withdrawal that size could trigger a crisis.”
“They’re mismanaging risk. Execute the redemption after the holidays.”
When I returned inside, James was pouring another scotch. He asked whether everything was fine, then immediately resumed explaining why I needed a real career.
I let him talk.
Over the next several days, his calls became desperate. On January 9, I finally answered.
“Daniel, thank God,” he said. “Our largest investor is pulling out $287 million. We’re being destroyed. You’re good with markets. Tell me what we’re missing.”
I took a slow breath.
“Your Asian expansion is over-leveraged,” I said. “If those markets correct, you could lose forty to fifty percent of your remaining capital.”
The line went silent.
“How do you know about our expansion?” he whispered. “That’s confidential information. We only share it with investors.”
“You share it with all investors,” I replied. “Including anonymous ones.”
Another silence followed.
“Daniel, what exactly are you saying?”
I looked through the window at my reflection.
“I’m saying I’ve been your largest investor for five years.”
Part 2: My Billion-Dollar Secret Shattered My Uncle’s Image of Me Forever.
For several seconds, neither of us spoke. I could hear the faint hum of traffic outside my penthouse and the steady ticking of the wall clock. On the other end, my uncle seemed unable to breathe normally.
“That’s impossible,” he finally said. “You’re a day trader. You live in a modest apartment. You drive an old Accord.”
“I live in a penthouse I own outright,” I answered. “I drive the Accord because it’s reliable. And I’m not a day trader.”
I let the next sentence land.
“I’m a private investor managing approximately $1.2 billion in portfolio assets.”
He repeated the number, barely audible.
“$1.2 billion?”
My father had left me $200,000. That part was true. What James had never understood was what happened afterward.
Within eighteen months, several concentrated investments had grown that inheritance to $8 million. Those gains didn’t make me a genius. They gave me the opportunity to keep learning, studying businesses, analyzing financial statements, and refining my approach to risk.
By the time I was thirty-one, I had approximately $35 million to invest. I continued compounding that capital, built relationships with other wealthy investors, and eventually began managing money for roughly thirty clients who valued privacy.
Today, my team included twelve people: Sarah, analysts, legal counsel, and compliance professionals. We worked remotely, shared secure databases, and met through encrypted video conferences.
I didn’t need a glass tower with my name on it.
“The $287 million you invested in MCP,” James said slowly. “You put that money into my firm?”
“Five years ago, I invested $35 million. It grew to $287 million. Your returns were solid when I came in, and your risk management looked sound.”
“But why didn’t you tell me?”
I almost laughed, but the sound never came.
“You never asked.”
The words were simple. The truth behind them wasn’t.
For five years, he had called my work a hobby. He had compared me unfavorably with Eduardo and Maria. He had offered me an entry-level position in the same firm where my capital had become its largest source of support.
“You told me I needed to learn from real professionals,” I reminded him. “You offered me a job as though I had nothing. You never once asked what I actually did.”
“We could have worked together,” he protested. “We could have been partners.”
“No. You wanted to help me. You didn’t want to know me.”
I explained that my decision to withdraw wasn’t revenge. MCP had begun taking excessive risks, and I had a responsibility to protect my capital and the money entrusted to me by my clients.
Six months earlier, my representatives had raised concerns about the firm’s growing exposure to Asia. James had dismissed those concerns as a failure to understand the opportunity.
“You ignored the warning,” I said. “The redemption stands. Transfer the $287 million by January 31.”
“This will destroy the firm.”
“Your risk management created the problem. I’m protecting my capital.”
When I ended the call, I expected relief.
Instead, I felt strangely hollow.
Within hours, the Martinez family WhatsApp group exploded. James had told everyone that I had secretly invested in his firm and then betrayed him by withdrawing at the worst possible moment.
Eduardo called first.
“You destroyed Uncle James’s company,” he accused.
“I withdrew my investment. Those aren’t the same thing.”
“You were family. You owed him loyalty.”
“I owe my clients responsible management. When a fund takes excessive risks, I leave.”
He scoffed when I mentioned my portfolio.
“You actually expect me to believe you manage $1.2 billion?”
“Call Sarah Chen at Clearwater Investment Holdings. She can verify it.”
He hung up.
Maria was different. She checked corporate filings before calling me.
“Clearwater Investment Holdings, Summit Capital Trust, Meridian Asset Group,” she said. “They trace back to you. Daniel, this is real.”
“Yes.”
“How much are you managing?”
“Approximately $1.2 billion.”
She went quiet.
“I manage a $600 million fund,” she finally said. “I thought I was doing well. And you’ve been doing this right under our noses?”
“I wasn’t hiding because I was ashamed,” I told her. “I was protecting my privacy.”
She asked why I hadn’t trusted the family enough to tell them.
I thought about Christmas. The laughter. The comparisons. The way James had used my father’s memory to make me feel small.
“Because you judged me before you ever tried to understand me,” I answered.
For once, Maria had no immediate reply.
Then she whispered, “We were wrong.”
“Yes,” I said. “You were.”
It was the first honest acknowledgment I’d heard from a Martinez relative in years. It should have felt satisfying.
Instead, I wondered how many of them would still believe me if the numbers were smaller, if the money disappeared, or if I never became successful enough to impress them.
The next few weeks would reveal more than my portfolio’s size ever could.
Part 3: The Market Turned, and My Uncle Finally Faced His Mistakes.
January 31 arrived with a hard deadline and a storm of phone calls. James’s firm was scrambling to prepare the redemption, while rumors about the anonymous investor spread among MCP’s remaining backers.
I knew the withdrawal would hurt. I also knew that delaying it simply because the investor and the fund manager shared a last name would have been irresponsible.
Sarah kept me informed.
“The redemption is moving forward,” she said during our morning call. “James is still asking whether you’ll reconsider.”
“I won’t.”
“He’s arguing that the expansion needs more time.”
“Then he can explain the risk to his remaining investors.”
Sarah paused. “You know the family will blame you.”
“They already do.”
The truth was that I had never wanted MCP to fail. I had invested because I believed in the firm. I had watched its performance for years, studied its reports, and trusted the discipline James once demonstrated.
But confidence had gradually turned into overconfidence. The firm began borrowing more, expanding into unfamiliar markets, and treating continued growth as though it were guaranteed.
I had seen that pattern before. Markets rewarded confidence until they didn’t.
On February 15, James finally called again.
“The redemption is processed,” he said without greeting me. “The $287 million is being wired to Clearwater today.”
“Thank you.”
He sounded exhausted.
“For what it’s worth, you were right. The Asian markets corrected last week. If we’d kept your money in that expansion strategy, we could have lost forty percent. Maybe fifty.”
I closed my eyes briefly.
“I’m sorry the market turned against you.”
“Are you?” he asked. “You sound awfully calm for someone who just destroyed his uncle’s firm.”
“I didn’t destroy it. I withdrew capital because the risk became unacceptable.”
He didn’t argue immediately.
MCP still had approximately $112 million in assets under management. It was far smaller than before, but it wasn’t finished. James had a chance to rebuild if he stopped chasing outsized returns and started protecting what remained.
“Deleverage,” I told him. “Reduce the exposure. Explain what happened to your investors. Show them what you’re changing.”
“Is that what you tell your clients when you make a mistake?”
“I tell them the truth. What went wrong, why it happened, and how we’re addressing it. Defensiveness destroys trust.”
He was silent for a while.
“You really understand this business,” he finally said. “This wasn’t luck.”
“I’ve spent fifteen years learning it. Not in boardrooms, but in the markets. I made mistakes, studied them, and built better processes. You did the same when you first started MCP. Then you stopped questioning your assumptions.”
“Complacency,” he admitted.
“Yes.”
He asked whether I would ever consider investing again if he repaired the firm.
“Possibly. But not because we’re family. I’ll look at your track record, your risk controls, and your decisions over time.”
He sounded wounded.
“I was your uncle.”
“And I was your largest investor. You treated me like a charity case because you never bothered to ask what I did.”
The words hurt him. I could hear it.
I didn’t enjoy that. But I wasn’t going to soften the truth simply to make him comfortable.
After we hung up, the family argument intensified. Some relatives accused me of humiliating James. Others quietly admitted that he had ignored warnings and taken risks that no responsible manager should have taken without understanding the downside.
Eduardo stopped boasting about Goldman Sachs around me. Maria began asking thoughtful questions about risk management rather than how much money I made.
I didn’t ask anyone to apologize.
What I wanted was simpler: for them to stop confusing appearances with ability.
In the weeks that followed, James began reducing MCP’s leverage and narrowing its focus. He had lost a great deal, but he had not lost everything.
I watched from a distance.
A manager could make a mistake and learn from it. Or make the same mistake again and call it bad luck.
The next family gathering would show me which path James intended to take.
Part 4: Easter Revealed How Much My Family Valued Money Over Understanding.
By Easter, the Martinez family gatherings had changed. The conversations were quieter, and James no longer dominated every discussion with stories about MCP’s returns.
His firm had stabilized, retaining roughly $95 million in assets under management from investors willing to give him another chance. He had reduced leverage, refocused on areas he understood, and begun rebuilding his risk controls.
The progress was real. So was the discomfort.
For years, I had been the family disappointment. Now relatives approached me with a new kind of attention. Some seemed impressed. Others appeared to be calculating what my success might mean for them.
I wasn’t sure which reaction bothered me more.
During dinner, Maria sat beside me and asked how my portfolio was performing.
“Well,” I said, “but that’s not the point.”
She smiled. “You manage more than a billion dollars. I think you’re allowed to enjoy that.”
“Managing a lot of money doesn’t make me a guru. It means I have a responsibility to the people who entrusted it to me.”
She leaned closer.
“People keep asking me about you. They want to know how you did it.”
“Tell them there’s no shortcut. There’s research, patience, and discipline. There’s also a lot of saying no.”
“Saying no to what?”
“Exciting opportunities that don’t meet your criteria. Investments that look profitable until you examine the downside. Managers who become convinced their success makes them untouchable.”
She understood immediately.
“Like James.”
“Like James.”
Across the room, Eduardo was talking to a relative about his work at Goldman Sachs. When he noticed me looking, he gave a small, uncomfortable nod instead of approaching with another offer to help me find a job.
I didn’t feel triumphant. I felt tired.
For years, I had thought that proving myself would silence the criticism. It hadn’t. It had merely changed the subject. People who once questioned whether I had a career now wanted investment advice, introductions, and explanations for how they could achieve similar results.
They wanted the outcome without the years of work behind it.
Maria seemed to read my expression.
“At least they respect you now,” she said.
“I didn’t do any of this to earn their respect.”
“Then why does it bother you?”
I considered that.
“Because I would have appreciated a little curiosity before the money. I didn’t need applause. I wanted someone to ask what I cared about instead of deciding I was a failure.”
She looked down at her plate.
“We really did make assumptions.”
“Yes.”
A moment later, Sarah sent my monthly portfolio report. Returns were up fourteen percent for the year so far, client satisfaction stood at ninety-six percent, and total assets under management had grown to $1.27 billion as existing clients increased their allocations.
Maria noticed me checking my phone.
“Work?”
“Always.”
“Do you ever take a break?”
“This is what I love. Researching businesses, understanding markets, managing risk, and helping clients grow their capital responsibly.”
She shook her head. “Most people would want to spend that kind of money.”
“Most people are free to spend their money however they want. I prefer building something that lasts.”
I had deliberately kept my life simple. The old Accord, the low profile, and the lack of an extravagant office weren’t signs of failure. They were choices that helped me concentrate on what mattered.
Then James approached.
He looked older than he had at Christmas. The confidence remained, but it no longer filled every inch of the room.
“Daniel, can we talk?”
“Of course.”
Maria excused herself, leaving us alone on the terrace.
The sun was setting over the Connecticut countryside. James stared at the lawn for several seconds before speaking.
“I’ve been thinking about what you said. About rebuilding MCP with better discipline.”
I waited.
“I wanted to run something by you.”
His next words surprised me.
“What if we partnered?”
Part 5: My Uncle Offered Me Partnership After Years of Calling Me a Failure.
James turned toward me, and for once, he wasn’t speaking as though he had already decided what I needed.
“Not you simply investing in MCP,” he clarified. “Actually working together. You bring your analytical skills and risk-management expertise. I bring the institutional relationships and operational infrastructure. We could build something special.”
I studied his expression.
Part of me remembered the man who had mocked me at Christmas. The man who offered me an entry-level job while sitting on top of a business funded largely by my capital. Another part remembered his voice on February 15, admitting that I had been right.
People could change. But promises weren’t proof.
“You want me to work for you?” I asked.
“With me. As an equal partner.”
“I don’t need a partner. I have a team, a process, and a structure that works. What would MCP give me that I don’t already have?”
His shoulders dropped slightly.
“Nothing, I suppose. I just thought we could build something together.”
“We can,” I said. “But not through a partnership agreement made because we’re family.”
He looked disappointed, though he tried to hide it.
I explained what I would need to see. Two or three years of consistent risk management. A track record that demonstrated discipline rather than spectacular returns. Evidence that MCP could resist the temptation to borrow heavily when markets were rising and everyone around James was making money.
“Then I’ll consider reinvesting,” I said.
“Always the professional,” he murmured.
“Especially because we’re family. If we partnered and the business failed, it could destroy our relationship. If I invest, I evaluate your performance. If your risk management deteriorates, I withdraw. We keep business and family separate.”
He gave a small, reluctant smile.
“No hurt feelings?”
“That’s the goal.”
“Daniel, I was devastated when you pulled out.”
“You were devastated because your risk management had failed. The withdrawal was a consequence, not the cause.”
He stared at me for a long moment.
“That’s a subtle distinction.”
“It’s an important one.”
We stood quietly as the last sunlight faded behind the trees.
Then James mentioned my father.
“Your dad would be proud of you. He always said you had a mind for numbers. That you noticed patterns other people missed. I thought he was being a proud father.”
“He usually was,” I said softly.
“I wish I’d asked you what you were doing instead of assuming I already knew.”
That was the closest thing to an apology I had received from him. It wasn’t perfect, and it didn’t erase Christmas, but it was honest.
“You’re asking now,” I told him. “That matters.”
Over the following months, I watched MCP from a distance. James continued reducing risk, reviewing the firm’s assumptions, and explaining difficult decisions to the investors who remained.
He was learning to accept slower returns in exchange for greater resilience. He was also learning that a good year did not prove a strategy was sound, just as a difficult year did not automatically mean a strategy had failed.
Those were lessons he had once tried to teach me.
Now he was learning them again.
Two years passed.
MCP stabilized at approximately $127 million in assets under management. The firm was smaller than it had been before the withdrawal, but it was profitable, more disciplined, and focused on strategies it understood.
Its returns were steady rather than spectacular.
That was exactly what I wanted to see.
After reviewing its improved performance, I made a decision with Sarah that I had once thought unlikely.
I would reinvest $50 million.
Not as a family favor. Not because James had apologized. And certainly not because I wanted him to know I had given him another chance.
The investment would come through the same anonymous structure.
Sarah reviewed the final paperwork with me.
“Are you sure?” she asked.
“I’m sure the numbers justify the decision.”
“And if James slips back into his old habits?”
“We leave.”
She nodded and prepared the documents.
The money was committed.
For the first time in years, I felt that the relationship between James and me might be moving toward something healthier. Not friendship built on admiration, and not a partnership built on family obligations.
Trust built on evidence.
I had no intention of announcing the investment. James had already learned that I was capable of withdrawing when necessary. Now he would have to demonstrate that he could earn and keep an investor’s confidence without knowing who was watching.
That was the only way the second chance would mean anything.
Part 6: My Secret Reinvestment Tested Whether My Uncle Had Truly Changed.
When MCP received the new $50 million commitment, James was relieved. He believed an anonymous investor had reviewed the firm’s recovery and decided that its improved discipline deserved another chance.
He didn’t know the renewed capital was mine.
He knew I had been the original $287 million investor who withdrew when the risk became unacceptable. But the new commitment came through the same anonymous investment structure, and no one confirmed the principal behind it.
Sarah handled the communications.
“We won’t let you down,” James told her during a call. “We’ve learned from our mistakes. We’re better managers now.”
“We believe your recent performance supports that assessment,” Sarah replied. “That’s why the investment is proceeding. But we will continue monitoring the risk metrics closely.”
“Of course. Please thank your principal for believing in us again.”
“I will.”
After she ended the call, Sarah turned toward me.
“He still doesn’t know this new investment is yours.”
“He doesn’t need to know.”
She studied me with the expression she reserved for decisions she considered unnecessarily complicated.
“Most people would want credit for giving a family member a second chance.”
“Most people measure success through recognition. I measure it through performance and risk management.”
“You’re a strange man, Daniel Martinez.”
“Efficient,” I corrected.
She laughed, and we returned to the quarterly report.
I expected the investment to remain uneventful. MCP had improved its controls, and James appeared to understand the mistakes that had nearly destroyed his firm. Still, I refused to assume that past progress guaranteed future discipline.
Markets had a way of exposing weaknesses people thought they had overcome.
Over the following months, the family continued discussing my finances. Some relatives wanted advice. Others wanted to know how I had accumulated so much wealth without buying a mansion or appearing in business magazines.
I declined most conversations.
My success wasn’t a secret formula that could be copied over dinner. It was the result of thousands of decisions, many of them boring, some of them painful, and all of them requiring patience.
I also knew how quickly admiration could turn into entitlement.
If I became the family’s unofficial investment adviser, every loss would become my fault and every gain would become proof that I owed them more help.
I preferred clear boundaries.
Maria understood. She continued managing her own fund, occasionally asking me to examine a risk assumption or discuss a market trend. Our conversations became more honest because neither of us pretended to have all the answers.
Eduardo remained more guarded. He no longer mocked my career, but he sometimes looked at me as though my success had rearranged the family hierarchy without his permission.
I felt no need to compete with him.
He had his career. I had mine.
James was the one I watched most closely.
He sent investors more detailed reports. He explained leverage, exposure, and downside scenarios without disguising uncertainty behind confident language. When a proposed acquisition failed to meet the firm’s risk criteria, MCP declined to pursue it—even though the projected returns were attractive.
Sarah brought the decision to my attention.
“That’s a meaningful change,” she said.
“Yes.”
“Two years ago, they might have taken that deal.”
“Two years ago, they were chasing growth.”
“And now?”
“Now they’re learning that not every opportunity deserves their capital.”
I approved the next stage of our monitoring process.
The $50 million remained invested, but the standards hadn’t changed. If MCP returned to excessive borrowing or ignored deteriorating risk metrics, we would exit. Family history would not alter the decision.
I wasn’t testing James to punish him.
I was testing whether his new discipline would survive the moment when abandoning it seemed profitable.
Then, late one autumn afternoon, Sarah called me with a report that made me stop reading.
“Daniel, MCP has a decision to make.”
I sat up.
“What kind of decision?”
“One that could tell us whether James has really changed.”
Part 7: A Sudden Market Shock Put My Uncle’s Hard-Won Discipline to the Test.
Sarah sent me MCP’s latest risk report before explaining the situation. A fresh wave of uncertainty was spreading through several markets, and some of the firm’s holdings were becoming more volatile than expected.
The issue wasn’t yet a crisis. It was a test.
MCP had identified an opportunity that could generate strong returns if conditions stabilized. But pursuing it would require additional borrowing and a larger exposure to markets already showing signs of strain.
Two years earlier, James might have viewed the opportunity as a chance to recover his firm’s former size. He might have focused on the projected gains and convinced himself that the warning signs were temporary.
Now he had to choose.
“Have they made a decision?” I asked.
“Not yet,” Sarah said. “Their investment committee is reviewing the downside scenarios. They can reduce the proposed position, proceed at the original size, or walk away entirely.”
“What do the numbers say?”
“The original position exceeds the firm’s revised risk limits. A smaller position would be manageable, but the expected return would be less exciting.”
I leaned back.
“Then the answer should be obvious.”
“Only if they’re serious about the new process.”
I understood her concern. It was easy to follow a rule when doing so cost you nothing. The real test came when discipline meant watching someone else make money while you stayed on the sidelines.
That evening, James sent a detailed update to MCP’s investors. He explained the opportunity, the uncertainty, and the limits of what the firm could responsibly risk.
Then came the decision.
MCP would decline the original transaction and consider only a smaller position if conditions improved. The firm would not increase leverage to chase a return that its own risk model could not justify.
Sarah read the notice twice.
“He did it,” she said.
“He followed his process.”
“Even though the projected returns were substantial.”
“Especially because the projected returns were substantial. That’s when people start making excuses.”
A few days later, market conditions worsened. The assets MCP had considered buying fell sharply, and firms that had borrowed heavily to pursue similar opportunities faced mounting pressure.
MCP avoided that exposure.
It wasn’t a spectacular victory. There was no celebratory headline, no dramatic announcement, and no sudden doubling of assets under management.
There was simply capital that had not been placed at unnecessary risk.
For James, that was the real achievement.
He had finally learned to value the money he didn’t lose as much as the money he could make.
I didn’t call to congratulate him. The investment structure remained anonymous, and the process was working as intended. But when Sarah presented our next review, I approved maintaining the position.
The decision wasn’t based on sentiment. It was based on evidence.
That distinction mattered to me.
Weeks later, I encountered James at a family dinner. He looked calmer than he had at the Christmas gathering that started everything. His conversation was less about impressive returns and more about the decisions his firm had declined to make.
“Sometimes the best investment is the one you don’t make,” he said to a relative.
I looked up from my plate.
For a moment, our eyes met.
He didn’t know about the latest investment decision I’d reviewed, but he knew what I had taught him during the worst period of his career. He had taken the lesson and made it part of his own process.
That was enough.
After dinner, he joined me outside.
“I used to think a good manager was someone who could spot the biggest opportunity,” he said. “Now I think it’s someone who knows which opportunities to leave alone.”
“That’s a better definition.”
He nodded.
“I wish I’d understood that before.”
“So do I.”
He didn’t ask me for money. He didn’t ask me to join his firm. He didn’t offer advice about my career.
For once, we stood together without either of us trying to prove anything.
And I realized that the most meaningful change wasn’t that James had finally respected my success.
It was that he had started questioning his own.
Part 8: I Finally Understood That My Worth Never Depended on Family Approval.
By the time my portfolio reached approximately $1.27 billion, the Martinez family had grown accustomed to the fact that I managed money professionally. The surprise had faded, although the questions had not.
Some relatives still wanted investment tips. Others asked whether I planned to buy a larger house, replace my Accord, or establish an office with a prestigious address.
I gave them the same answer.
“I’m happy with the way I live.”
It wasn’t false modesty. I had built a life around the work I enjoyed, and I saw no reason to change it simply because other people had discovered the size of my portfolio.
My penthouse was comfortable. My car was reliable. My team had the resources it needed, and my clients trusted us to make careful decisions with their capital.
That was enough.
Sarah continued overseeing our operations, and we reviewed performance reports, client allocations, and risk exposure with the same discipline we had maintained for years. We celebrated strong results, but we never treated them as proof that we could stop being careful.
Returns could change. Markets could turn. A strategy that worked yesterday could fail tomorrow.
The process had to remain stronger than the excitement of any individual result.
One afternoon, Maria called to ask whether I had ever regretted keeping my success private.
I considered the question.
“Sometimes I regret that I let people misunderstand me for so long,” I admitted. “But I don’t regret protecting my privacy.”
“Even after everything with James?”
“Especially after everything with James. If I’d told the family about my money earlier, some of them might have treated me differently. But I wouldn’t have known whether they respected me or the number.”
She was quiet.
“That’s fair.”
I explained that I had never needed the family to understand every investment decision. I had needed them to stop deciding what kind of person I was based on my apartment, my car, or my job title.
That distinction had taken me years to articulate.
I had spent so long refusing to defend myself that I sometimes confused silence with strength. In reality, I could have told them the truth at any time. I simply hadn’t believed their approval was worth the conversation.
Christmas proved that I had been right about their assumptions, but it also forced me to confront something uncomfortable.
I couldn’t control what people believed about me. I could control whether I allowed their opinions to determine my choices.
James eventually became more comfortable discussing his mistakes. He no longer described MCP’s earlier success as evidence that every decision had been correct. Instead, he talked about the danger of becoming attached to a winning strategy and the importance of challenging assumptions before the market did it for you.
His firm remained smaller than it once had been, but its approach was more measured. The renewed investment stayed subject to the same monitoring requirements as every other position in my portfolio.
No exceptions.
At a later family gathering, James approached me while I was reviewing a message from Sarah.
“Still working?” he asked.
“Always.”
He smiled. “I used to think you were wasting your life sitting behind a laptop.”
“I remember.”
“I was wrong.”
He didn’t make excuses or blame the pressure of running a firm. He simply acknowledged it.
That mattered more than a grand apology would have.
“Thank you,” I said.
He looked toward the house, where our relatives were talking over dinner.
“I wish I’d asked more questions.”
“So do I.”
We stood quietly for a moment. There was no need to turn the conversation into another lesson.
My father had always believed I could see patterns other people missed. I had carried that belief with me through the early years, when my inheritance grew and I learned that a profitable decision could still be a reckless one if the downside wasn’t understood.
I had carried it through the years when my family mistook modest living for failure.
And I had carried it through the decision to withdraw $287 million from my uncle’s firm, even when I knew the consequences would be painful.
I never wanted to destroy James’s business. I wanted to protect the capital I was responsible for managing. The fact that he was my uncle made the decision harder, not less necessary.
Eventually, the family stopped treating my work as a mystery and started treating it as work. Eduardo became more respectful. Maria and I developed a more honest professional relationship. James rebuilt his firm by learning to value discipline over appearances.
None of that happened because I bought a yacht or announced my net worth at Christmas.
It happened because I kept doing the work.
Today, I still drive the Accord. I still prefer quiet mornings with market reports to crowded rooms full of people comparing achievements. I still review risks before chasing returns, and I still believe that protecting capital matters more than receiving credit for growing it.
The lesson wasn’t that money makes people respect you.
The lesson was that money reveals what people were willing to assume about you before they knew the truth.
My uncle had once looked at me and seen a failed day trader. I had looked at his firm and seen risks he refused to acknowledge. We were both forced to confront what we had misunderstood, but only one of those misunderstandings threatened hundreds of millions of dollars.
James learned to question his assumptions.
I learned that I didn’t need to correct every assumption others made about me.
And the work continued.
The research. The analysis. The patient discipline of managing capital responsibly.
That was what mattered when the market was rising, when it was falling, and when nobody was watching.
I no longer needed my family to recognize my success before I could believe in it myself.
They could talk about my car, my home, or the fact that I worked from a laptop. They could speculate about what I owned or wonder why I didn’t live like someone managing more than a billion dollars.
I knew what I had built.
I knew what it required to maintain it.
And I knew that the next difficult decision would not become easier simply because someone shared my last name.
In the end, I hadn’t won an argument with my uncle. I had learned to protect what mattered without needing him to agree with me.
His respect was welcome, but it was never the objective.
The objective was always the work.
And that was where I intended to remain.
THE END