“YOU REALLY CAN’T STAND SEEING ME HAPPY?” my sister texted after I stopped sending Mom and Dad $600 every month. They’d forgotten my thirty-first birthday but surprised her with a pearl-white SUV wrapped in a giant red bow. I stared at my lonely slice of birthday cake, remembering the $28,800 I’d paid them. Then she mentioned the car payments.
“YOU REALLY CAN’T STAND SEEING ME HAPPY?” my sister texted after I stopped sending Mom and Dad $600 every month. They’d forgotten my thirty-first birthday but surprised her with a pearl-white SUV wrapped in a giant red bow. I stared at my lonely slice of birthday cake, remembering the $28,800 I’d paid them. Then she mentioned the car payments.
PART 1 — My Forgotten Birthday Came With a Very Expensive Surprise
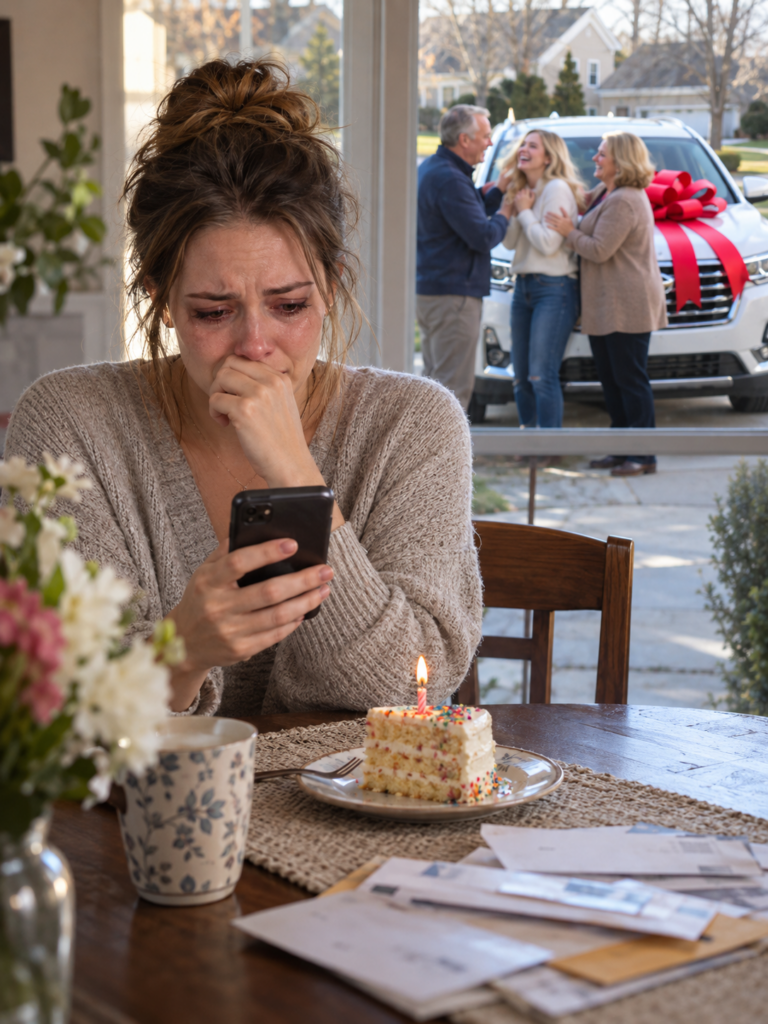
The first person to mention my thirty-first birthday was the pharmacist who checked my driver’s license when I picked up allergy medication. My parents didn’t call. Neither did my sister. At 8:43 that evening, though, my phone showed a photo of Brooke standing beside a pearl-white SUV with a red bow across the hood.
“Best parents in the world,” her caption read.
Dad had commented, “You deserve every bit of it, sweetheart.” Mom had added three hearts. I was sitting on my apartment floor, sorting bills into a folder because the kitchen table was covered with work papers. I looked at the cake slice my friend Naomi had dropped off that afternoon, then back at the picture.
I typed, “Congratulations, Brooke.”
It wasn’t sarcasm, exactly. She had a new car. Congratulations seemed appropriate. But I didn’t have it in me to add a heart.
My name is Claire Benton. I’m an accountant for a commercial building-supply company in Chattanooga, Tennessee. I drive a twelve-year-old Honda, rent a one-bedroom apartment, and have been saving for a down payment since I turned twenty-seven. In my family, that apparently qualified me as the daughter who didn’t need anything else.
Brooke was twenty-eight, charming when she wanted to be, and always halfway through reinventing herself. She sold furniture at a showroom, which meant her commissions rose and fell. When she earned well, she celebrated. When she didn’t, Mom and Dad called it a rough patch and stepped in.
I used to think I was imagining the difference. Then, five years earlier, I finished a difficult accounting certification while working full-time. My employer held a recognition luncheon and offered two seats for family. My parents promised they’d come. That morning, Brooke needed help moving apartments, and both of them went to rent a truck instead.
Mom said, “You understand, honey. You’ve always been independent.”
I smiled through the luncheon while my supervisor took a photo for my parents. Mom responded to it with a thumbs-up emoji. I still have the certificate, although the photo stayed buried in my email.
When Dad retired early four years ago from his administrative job at an insurance company, I wanted to help. He and Mom still owned their house, and Mom worked part-time at a home-goods store, but his smaller retirement income made their monthly budget tighter. At their kitchen table, Dad showed me the mortgage payment, property taxes, utilities, and groceries.
“Could you manage six hundred a month while we adjust?” he asked. “Just until we get our footing.”
I could, barely. I set up an automatic transfer. Three months later, when I asked whether they’d figured out a new budget, Dad said the furnace had needed repairs. A few months after that, it was the washing machine. Both expenses were real. Each time, I figured another season wouldn’t hurt.
Then Dad asked me to consolidate our cell phones under an account in my name. Four lines came to around $180 a month, including mine. It was cheaper than the plan my parents had before. I agreed, and eventually stopped noticing the charge.
I passed on vacations, kept the Honda through another expensive repair, and searched real-estate listings without making offers. When I mentioned how long saving was taking, Mom told me I was lucky to have a steady paycheck. She wasn’t wrong. She also never asked where that paycheck went.
A few weeks before my birthday, Dad called as I was leaving work. He wanted to know if my $600 would continue through the end of the year.
“I need to check my own budget,” I told him. “I can’t promise it forever.”
He said he understood, then mentioned they were helping Brooke with transportation. Her old car had become unreliable. I assumed that meant paying for repairs or helping with a used car. He didn’t offer details, and I had become skilled at not asking questions likely to end in an argument.
Now I stared at the bow on that SUV. The model was nicer than anything I’d ever owned. Maybe my parents had saved up for it. Maybe Brooke had gotten an unbelievable dealership deal. I didn’t know, and I wasn’t entitled to the details of her financing. What I was entitled to was decide what happened to my paycheck next.
I opened my banking app. Forty-eight automatic payments of $600 came to $28,800. Still, seeing the total made me set the phone on the counter.
That money had been given willingly. I didn’t intend to demand it back. But I remembered turning down a weekend trip with Naomi because my savings were behind. I remembered my Honda breaking down outside a grocery store while I worried about the cost of a tow. I remembered Dad asking about the payments while failing, once again, to ask how I was doing.
The next transfer was due in six days. I canceled it, saved the confirmation, and drafted an email explaining that my voluntary household support was ending. I also checked the phone account. Two devices still had installment balances, and I was responsible for the bill as account holder. I couldn’t simply stop paying, so I looked up the carrier’s procedure for moving the other three numbers to separate accounts.
My email offered to keep the phone service current while we completed that process. I would not authorize new devices or charges. I read it twice, removed an angry sentence about birthdays, and pressed Send.
At 7:12 the next morning, Mom left a voicemail: “You can’t make decisions like this without talking to us.” Dad emailed asking why I’d chosen such terrible timing. Brooke sent a message that started with, “You really can’t stand seeing me happy, can you?”
I went to work anyway. During lunch, another message arrived from Brooke: “They promised to help with my car payments. What am I supposed to do now?”
Payments. Plural. Until that moment, I’d assumed the giant red bow represented a gift my parents had already paid for.
PART 2 — My Sister’s Car Loan Turned My Gift Into Their Budget
I called Brooke after work, standing beside my Honda in the office parking lot. A delivery truck was backing into the warehouse, and the warning beeps almost drowned her out.
“The loan is in my name,” she said, irritated that I’d asked. “Mom and Dad are putting in three-fifty a month until my commissions pick up. They promised.”
“Did anyone ask if I could keep sending six hundred?”
“Why would they? You’ve been doing it for years.”
I had to hold the phone away from my face for a second. Brooke wasn’t pretending the two arrangements were connected; to her, the money simply existed. She knew about my house fund, but never treated it as something remotely real. She told me she needed a reliable vehicle for work and that I’d never supported her success. I looked at my Honda’s cracked dashboard and told her I hoped the SUV worked out. Then I ended the call.
At home, I checked my credit reports through the authorized service I already used. There was no auto loan in my name. It was a relief, though not much of one. My parents had committed money they couldn’t comfortably spare, and Brooke expected them to find it somewhere.
Dad’s next email said he’d built the household budget around my contribution. He called my cancellation abrupt. On that point, I couldn’t entirely disagree: six days wasn’t much notice. But I’d warned him weeks earlier that I couldn’t commit indefinitely. He had chosen to proceed anyway. I replied that I wasn’t asking for past payments back and would help transfer the phone lines, but the bank transfer would not resume.
Mom called me ungrateful. Then she told her younger sister, Aunt Ruth, that I had stopped helping because I was jealous of Brooke’s new car.
Ruth phoned me that night. “Your mother says you’ve left them without grocery money.”
“That’s not what Dad’s budget showed when he asked me to help.”
I sent her the dates and total of my transfers, not my bank statements. I explained that both my parents still had income and that I hadn’t agreed to finance Brooke’s new commitment. Ruth didn’t take my side immediately. She asked whether I had ever checked in about their expenses. I admitted I’d stopped trying after Dad repeatedly said they needed more time.
“Then you all let an arrangement become an expectation,” she said. “But only one of you was paying for that assumption.”
Naomi, my closest friend, was less diplomatic. Over takeout noodles, she asked why I felt guilty about having a savings account. She also reminded me to check every contract with my name on it. I made a list: bank transfer canceled, phone installments verified, credit reports checked, line transfers pending.
That night, Dad sent another email. He wanted me to continue contributing until Brooke had made several car payments. Under his signature was a sentence I read three times: “We made commitments based on what we knew we could count on.”
PART 3 — At My Kitchen Table, Everyone Wanted a Different Answer
I agreed to a meeting at my apartment on Thursday, provided Aunt Ruth could attend. Mom protested that Ruth was an outsider. I pointed out that Mom had already invited her into the dispute by calling me jealous. That ended the objection, if not the resentment.
Before they arrived, I printed the original email describing my support as temporary, my current notice, and the phone carrier’s transfer instructions. I had no intention of presenting forty-eight bank statements like courtroom exhibits. The folder was there in case anyone claimed I had never warned them.
Mom arrived carrying the expression she used when a store clerk refused an expired coupon. Dad followed, looking older than he had two weeks earlier. Brooke wore a showroom blazer and kept her car keys in her hand.
“This has gotten completely out of proportion,” Mom said before sitting down. “It’s six hundred dollars, Claire.”
“It’s six hundred dollars every month.”
Dad asked for ninety more days. He explained that the mortgage, utilities, and insurance were already scheduled, and changing things would take time. I believed him. That was what made the conversation harder. There were real bills behind his frustration, and I’d spent four years worrying about them.
“Why didn’t you tell me you were counting on it permanently?” I asked.
“We didn’t think we had to,” he said. “You were managing fine.”
I told him about my down-payment account and the repairs I’d postponed. He looked surprised that I had a target date for buying a home. Mom said she’d never heard me complain. I reminded her of the evening I’d mentioned how expensive houses were getting and she’d suggested I work another weekend.
Brooke leaned forward. “You’re making it sound like they bought my car with your money. They didn’t.”
“I’m not saying they did. I’m asking why they promised to help with it before confirming they could afford to.”
She answered that her old sedan had become unsafe and that she needed to reach weekend appointments. I understood the need for transportation. I didn’t understand why she’d chosen a vehicle whose payments depended on three other adults rearranging their finances.
Ruth arrived as Dad pulled a folded budget from his coat pocket, marked in pencil. He flattened it on the table, showing how their regular expenses added up. My contribution appeared on the income side, just below his retirement deposit.
He tapped the line with his finger. “I used the money coming in when I worked out what we could offer Brooke.”
There it was: not a secret account or a forged signature, just a decision made about my future without inviting me into the room.
Mom studied my face, then switched tactics. “Fine. We’ll have a proper birthday dinner this Sunday. Your favorite meal, a cake, all of us together. We can get back to normal.”
For one awful second, I wanted to say yes. Then Dad slid the budget toward me again, as though a dinner could make its numbers work.
PART 4 — The Birthday Dinner Offer Exposed What They Expected Back
Ruth broke the silence. “Linda, is the dinner an apology, or are you asking Claire to start paying again?”
Mom drew her purse into her lap. “I want my family together. Is that somehow wrong?”
“No,” I said. “But you didn’t ask what I wanted for my birthday. You asked what would make me stop being difficult.”
Mom said adults didn’t need their parents making a fuss over birthdays. I asked why Brooke got a celebration whenever she changed jobs or moved. Mom answered that Brooke needed encouragement. I thought about the certification luncheon they’d skipped to help her move and told them about the empty seats. Dad remembered the truck rental. Mom remembered that Brooke had been overwhelmed. Neither remembered asking how my luncheon went.
“She’s your sister,” Mom said. “You know she’s had a harder time getting settled.”
“Maybe. But I’m not a household utility you can leave running because I’m dependable.”
Dad pushed the budget back into his folder. His voice was controlled. “I wasn’t trying to take advantage of you. We had an arrangement, and I thought I could rely on it.”
“You could rely on it until I said I needed to reconsider. I told you that before Brooke bought the car.”
He didn’t dispute it. Instead, he asked whether I could reduce the support gradually. With ninety days, he said, they could cut subscriptions and adjust spending without missing a bill. I considered it. I was not eager to make my parents’ lives difficult. But I’d spent years extending an agreement that was supposed to last months. If I offered another deadline they could ignore, I knew exactly who would feel responsible when it arrived.
“No more transfers,” I said. “I will pay what I’m legally responsible for on the phone account while we move the lines. That’s it.”
Brooke set her keys on the table. “So I get stuck with a payment I can’t afford?”
“You signed for the car, Brooke. Ask the lender about your options. Work out a budget. I can show you how, but I won’t pay it for you.”
She scoffed at the offer, and I let it go.
Ruth asked Dad whether their retirement and wages covered the essentials if they reduced spending. He admitted they did, though there wasn’t much left afterward. Mom stared at him. Brooke looked down at her own keys.
I handed Dad the carrier paperwork and explained the deadline to accept line transfers. I told him nobody would lose service while we handled the existing installments correctly. He took the pages without arguing.
At the door, Mom asked if Sunday dinner was canceled. I said I wasn’t ready for a birthday dinner, especially one designed to settle an account. She went down the stairs without another word. Dad paused, as if he might finally ask how I had spent my birthday. He only said, “I didn’t realize you’d been saving that seriously.”
The folder stayed under his arm as he followed her outside.
PART 5 — I Stopped Funding Their Plans and Started Making My Own
The first canceled transfer stayed in my checking account the following Tuesday. I moved the $600 into my house fund before I could second-guess myself. I expected relief. Instead, I felt strange making breakfast without wondering whether Mom would call to tell me what I’d done wrong.
There were still loose ends. Dad completed the phone transfer forms for himself and Mom, but Brooke ignored the carrier’s requests until the authorization was about to expire. I sent her one practical reminder with the deadline and nothing else. She opened her own account, arranged for her remaining device balance to move with her, and confirmed the change. I paid the final charges that belonged to me and saved the closing statement.
Aunt Ruth heard that Dad had canceled two streaming subscriptions, postponed replacing the living-room furniture, and started tracking expenses again. Mom took an extra shift each week at the store. They still lived in the same house. The emergency everyone predicted hadn’t happened; they’d simply had to change the way they spent their money.
Brooke picked up weekend appointments at the showroom. Eventually she contacted her lender about selling the SUV and discovered she owed more than a private buyer was likely to pay. She kept it for now, cut other expenses, and complained to Ruth that her life had become nothing but work.
Mom emailed twice. First she offered to cook my favorite dinner. Then she said our family had never been good at talking about feelings. Neither message mentioned the story she’d told Ruth about jealousy or the years I’d quietly helped. Dad sent a shorter note acknowledging that he should have asked before assuming my contribution would continue. I read it more than once.
I replied to all three of them together. The phone arrangements were complete, I wrote, and I wouldn’t be sending money or discussing that decision again. I needed an indefinite break from visits and calls. Please don’t contact me. I had to rewrite that last sentence because my first version included an apology I didn’t mean.
After sending it, I blocked their numbers. I told Ruth we could stay close as long as she wasn’t asked to carry messages between us. She agreed, and the next time we met for lunch we talked about her ridiculous office coffee machine instead of my parents.
Naomi came with me to look at two small houses on a rainy Saturday. Both needed work, and neither felt right. I hadn’t magically accumulated a down payment in a month, but I’d received a realistic mortgage preapproval and could finally save without somebody else assigning the money a purpose. I also enrolled in a course at work I’d put off because of the cost.
At the third open house, I stood in a narrow kitchen with worn blue cabinets. The agent asked whether I’d like another look before leaving. I slipped my phone into my coat pocket, walked back toward the kitchen window, and said, “Yes, actually. I would.”
THE END
You Might Also Enjoy
My Roommate’s AC Died in the Heatwave… She Stood at My Door in a Robe “Can I Sleep in Here Tonight?”
I Gave a Stranger My Address in Case She Needed Help… 3 Days Later, She Actually Showed Up