For three years, I paid my parents’ mortgage and taxes while sacrificing my own dreams. Then Mom excluded me from their thirtieth anniversary dinner, and my sister posted a smiling photo captioned “Family only.” Even strangers had seats where I didn’t. I commented, “Congratulations. The mortgage and taxes are yours now.” Within minutes, the photo vanished and thirty calls flooded my phone. I thought they feared losing my money—until a bank email revealed my signature on a loan I’d never approved…
Part 2/5
As my relatives demand that I keep paying, I cancel automatic transfers, protect my job, and uncover an alarming refinance document bearing my signature.
I slept with my phone turned over on the nightstand, listening to it vibrate against the wood. By morning, the missed calls were accompanied by messages from my mother, my sister, and cousins who hadn’t spoken to me in years.
“You’ve embarrassed us,” Mom wrote. “After everything we’ve done for you, how could you be so cruel?”
Callie’s version was less polished. “You’re making our anniversary about yourself again. Delete your comment and tell everyone you were joking.”
I almost laughed at the phrase “our anniversary.” It belonged to my parents, but somehow Callie owned the event, the photographs, and the right to decide who counted as family.
The comments were already gone; she’d erased them along with the picture. What she really wanted deleted was the thought that their beautiful house and perfect celebration had been supported by someone outside the frame.
I opened my banking app before work. For three years I’d set those payments to run automatically, and looking at the future schedule made me feel as though my bank account had been annexed without anyone asking.
I canceled the mortgage transfer, canceled the separate tax payment, and placed any remaining connected instructions behind manual approval. I took screenshots of each confirmation and wrote down the date, because I had learned on construction sites that the best defense against confusion is a clean record.
I was stopping voluntary payments, not pretending a button could erase any legal obligation. My name had never been supposed to belong on their home loan, and I wanted to verify that before I assumed anything else.
By lunchtime, the family campaign had moved online. Callie posted a solemn picture holding Mom’s hand and wrote about adult children who “forget who raised them” once they start earning good money.
A few hours later, someone called the reception desk at my architecture firm. The caller claimed to be family, insisted I was behaving irrationally, and demanded my direct number and work schedule.
My manager, Daniel Cross, brought me into his office. “Whatever is happening at home, Evan, I need you to protect our clients and our staff from it,” he said.
His disappointment hurt more than I expected. I had spent years being the employee who never let a personal crisis interfere with a deadline, and now my relatives were trying to make me look unstable where my work actually mattered.
I told Daniel that there was a family financial dispute and that I was handling it formally. He agreed to send further calls to human resources, but his warning was clear: the situation could not become everybody else’s problem.
Renee met me outside his office. “Save every message,” she said. “And check every device connected to your accounts; people who are only offended don’t usually call somebody’s employer.”
That evening I changed passwords, removed old login permissions, and copied the family’s messages into a dated folder. I checked my banking email again, this time refusing to let a familiar logo persuade me that everything was routine.
The odd message was real. Inside was a reference number and an attached document titled “Refinance Agreement.”
I opened the file and recognized my childhood address in Charleston. My parents’ names appeared where I expected them, followed by mine in a section reserved for an additional obligated signer.
The document listed a loan larger than the mortgage I’d been helping pay. It included a cash-out amount, revised terms, and an electronic signature that looked official enough to make my stomach turn.
“Evan Mercer,” the signature read. Below it were a date in July and a digital verification record.
I’d never applied for a refinance. I’d never discussed borrowing more against that house, and I certainly hadn’t signed a document making myself responsible for it.
A heavy envelope had arrived at my apartment that afternoon, buried under grocery advertisements. I opened it now and found a formal lender notice referencing the same agreement and my supposed role in it.
The totals were frightening, but the timing was worse. My parents had increased the debt while I was continuing to pay the old bills, apparently confident I wouldn’t ask where the money was going.
I called the bank using the number on its official website rather than anything in the email. After two transfers, a representative named Owen Bell pulled up the file and confirmed that the refinance had been processed in July.
“I did not authorize this,” I told him. “I need the signature records and the authentication history, and I want a formal dispute opened.”
He became careful and professional. He couldn’t determine wrongdoing over the phone, he explained, but he could begin an investigation and direct me to the written dispute process.
Then he asked whether I’d ever shared access credentials or verification codes with anyone connected to the property. The memory of Mom’s casual phone call returned so sharply that I gripped the edge of the table.
I told him about the code. Admitting it felt humiliating, but leaving it out would only make an already difficult situation harder to untangle.
Owen opened a case and instructed me to send identification, a written statement, relevant messages, and whatever proof I had of the unauthorized signature. When I hung up, my phone showed another text from Mom.
“Please don’t involve strangers in our business,” she wrote. “We can explain everything.”
She hadn’t said there was no refinance. That omission scared me more than any insult Callie had posted.
Part 3/5
The bank’s records connect suspicious approvals to a code my mother requested, while escalating threats force me to seek legal help and confront them.
I spent the next morning reconstructing July. The bank’s messages were timestamped, my work calendar showed where I had been, and my phone still held the conversation in which Mom requested a security code “for the house.”
Two approval events had been recorded within minutes of that request. They didn’t prove who had pressed every button, but they proved I hadn’t been told the truth about what I was authorizing.
I sent Owen a careful statement explaining that I’d supplied a code under a false understanding and had never agreed to borrow money or guarantee a refinance. He acknowledged the dispute and said the review team would examine the electronic records.
Then I checked my credit reports. A lending inquiry appeared near the date of the transaction, one I hadn’t initiated and hadn’t noticed because I’d trusted that my finances were my own.
I placed additional security measures on my credit files and removed every remembered device from my account. One old login session looked unfamiliar; I saved what the interface showed before revoking it, careful not to treat suspicion as proof.
My mother called fourteen times that day. When I refused to answer, her messages shifted from indignation to fear: “Do you want your father to lose his home?” and “The neighbors will think we’ve done something terrible.”
Callie sent something uglier. “Keep making trouble and I’ll tell your boss what kind of person you really are.”
Soon a message arrived in the firm’s general inbox suggesting that I was emotionally unstable and abandoning my parents. Daniel and HR documented it, restricted future contact, and reminded me that my colleagues would not become an audience for my relatives’ accusations.
Renee helped me organize my materials into folders: payments, correspondence, bank records, and attempts to contact my employer. We did not turn the documents into a public spectacle; I had already learned how dangerous it was when Callie controlled the story online.
“You need somebody who knows how to fight this on paper,” she told me. “Not another conversation with your mother.”
I contacted a lawyer named Nora Whitcomb, whose practice handled real estate and unauthorized financial agreements. During our first call she asked direct questions about the title, the loan documents, my payments, and exactly when I’d first learned of the refinance.
She didn’t promise that a bank investigation would magically fix everything. She said electronic verification could make the dispute complicated, especially because I had voluntarily given Mom a code, but consent to help with paperwork was not the same as consent to become a borrower.
“We establish what you understood, what you agreed to, and who benefited,” Nora explained. “We preserve the evidence. We let the formal process do its work.”
She prepared a notice of representation, requested the bank records, and instructed my family to stop contacting my workplace. She warned me not to record private conversations without checking the law or to stage a confrontation that created new problems.
The next day Owen confirmed that the disputed approvals had been carried out through an online portal connected to my credentials. Full technical findings were pending, but the dates aligned with the code request I’d preserved.
I spread my bank statements across the kitchen table. Three years of mortgage drafts, separate property-tax transfers, and emergency extras added up to a sum large enough to make me wonder how differently my own life might have looked without them.
A week after the dinner, Callie surprised me with a gentle text. “Can we meet for brunch in Charleston? Mom wants us to work this out privately; no outsiders, no lawyers, just family.”
I forwarded it to Nora. She told me I didn’t need to attend, but if I chose to have a conversation, I should keep it brief, avoid discussing settlement terms, and put any substantive agreement through counsel afterward.
I decided to go, not because I expected an apology, but because I wanted to hear my family answer one question while looking at me: Why had they used my name?
I booked a flight and packed a slim folder of copies rather than the originals. On the plane, I stared at the clouds and remembered my father teaching me to measure twice before cutting wood in the garage of the house I had since spent years trying to save.
Dad had always been quiet when Mom was angry. I used to call that gentleness, but the older I became, the more his silence resembled permission.
Charleston greeted me with humid air and familiar streets. I passed porches decorated with hanging ferns, parked near the café Callie had chosen, and arrived early enough to settle my nerves over a glass of water.
Through the tall windows I could see an American flag moving gently outside a shop across the street. It was a perfectly ordinary morning, which made the folder beside my glass feel even heavier.
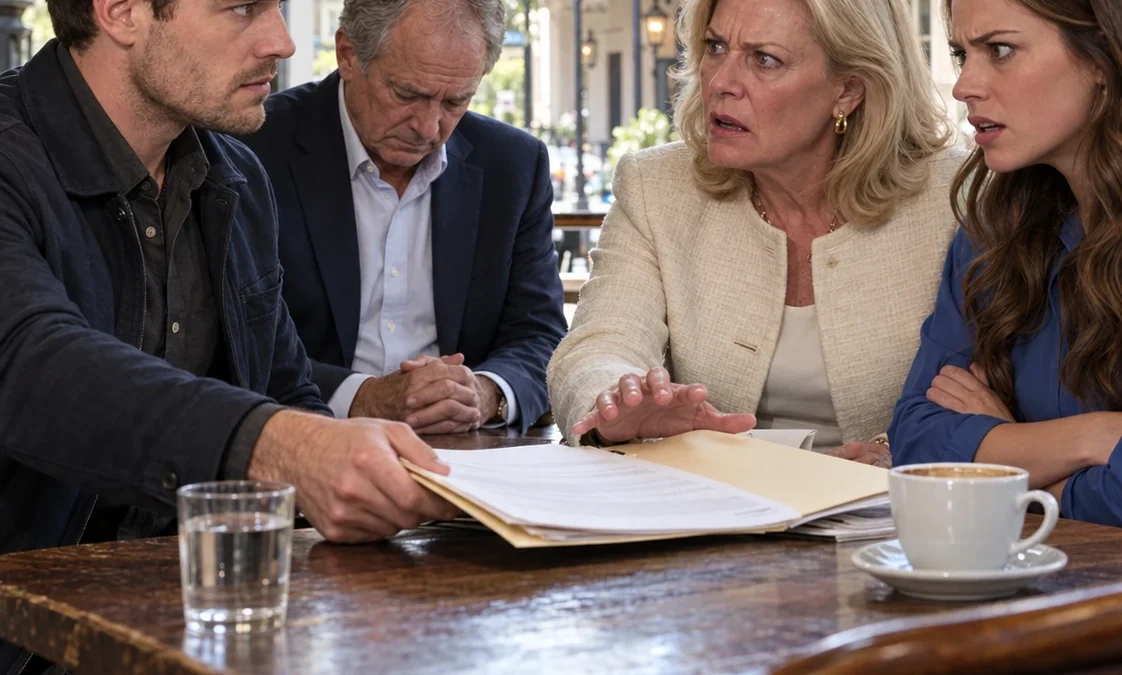
My mother arrived first, immaculate in a cream jacket. Callie followed in a tailored blue blouse, her smile prepared for an audience, and Dad came last with the exhausted expression of a man who hoped other people would decide everything for him.
They sat down together. Mom reached for my hand, and when I moved it onto the folder instead, she sighed as though I’d already ruined the meeting.
“Let’s forget that embarrassing Facebook incident,” she began. “We have bigger things to discuss.”
“I know,” I said, opening the folder. “That’s why I brought the bank documents.”
Part 4/5
At a Charleston café, I confront my parents with the unauthorized loan, expose my sister’s financial connection, and finally refuse their demands.
I slid the refinance agreement across the table. Mom glanced down, then looked toward the windows, checking who might be close enough to overhear.
“You never told me I was becoming responsible for another loan,” I said. “You asked me for a code and described it as ordinary paperwork.”
Callie folded her arms. “Banks make mistakes, Evan. You’re acting like we broke into your apartment.”
“Then tell me who signed my name,” I replied. “And why the confirmation was sent to me for a transaction I never approved.”
Mom’s composure flickered. Dad straightened in his chair, but neither of them denied that the transaction had taken place.
“We were under pressure,” Mom finally said. “You can’t understand what it feels like to think you might lose everything you’ve worked for.”
I looked at her expensive jacket, at the manicured nails resting beside the café menu, and thought of the unopened card she’d mailed back to me. “I’ve been paying to protect that house for three years. What exactly were you protecting?”
“The family,” she whispered.
“Which part?” I asked. “The part allowed at your dinner, or the part expected to pay for it?”
Callie’s chair scraped the floor. “Oh, here we go; this is all because you didn’t get invited, isn’t it? You always need somebody to tell you you’re special.”
“The invitation showed me how you see me,” I said. “The signature showed me what you were prepared to do about it. Those are two different things.”
I pointed to the additional borrowing shown in the agreement. “The refinance wasn’t only about lowering a payment; there was money taken out. Where did it go?”
Mom said nothing. Callie looked quickly toward Dad, who stared at his hands.
“You already know,” I said, because their expressions made the question almost unnecessary. “Does this have something to do with Callie’s debts?”
“She was in trouble,” Dad said, finally speaking so quietly I almost missed it. “We thought there would be time to straighten it out.”
Mom turned toward him, furious. “Graham, that is not helping.”
He fell silent, but it was too late to put his words back. I felt an awful shift inside me, as though a door I’d spent years trying to open had finally revealed a room I never wanted to see.
Callie lifted her chin. “I had some bills; everybody does. Mom and Dad wanted to help me.”
“With a loan carrying my signature?” I asked.
“You always had a good job,” she snapped. “They knew you wouldn’t let anything happen to the house.”
There it was. Not an apology or even a believable misunderstanding, but a calculation based on my reliability.
Mom leaned forward. “We meant to explain once things settled down. You were never supposed to be burdened with any of this.”
I turned the page so she could see my name in the obligation section. “Then why is my name here instead of just yours?”
She looked away. “The bank needed reassurance.”
“You mean the bank needed me,” I said. “And you didn’t think I’d say yes if you asked.”
Callie’s eyes shone with anger. “If you send all this to the bank, you could destroy Mom and Dad. Is that what you want?”
“I’ve already reported the unauthorized agreement,” I replied. “A lawyer is handling it. If you’d asked me for help, I could have decided what I was willing to give; you took away the decision.”
Mom’s face hardened into the expression that used to end every argument when I was a child. “Family doesn’t turn against family over paperwork.”
“Family doesn’t sign someone else’s name to paperwork,” I said.
I explained the boundaries I’d come to state in person. The automatic payments were canceled; I would not guarantee their debts; any future financial discussion had to go through Nora; and contact with my employer had to stop.
Dad rubbed his forehead. I wanted him to tell me he had tried to stop it, but the closest he came was a defeated, “We didn’t think it would come to this.”
“Neither did I,” I said.
Mom’s eyes filled, and for one dangerous second I wanted to comfort her. Then she whispered, “What will people say if we lose the house?” and I understood that even now she was watching an imaginary audience.
I stood and collected my papers. Callie said I was selfish, Mom called my name, and Dad kept his gaze on the table as I left them behind.
Back in Denver, Nora continued requesting records through the dispute process. Owen later confirmed that the digital approvals had been made from an access pattern and location consistent with Charleston, and additional review showed the cash-out money had not all gone toward preserving the house.
Some funds covered delinquent charges and fees, but a significant portion paid high-interest obligations associated with Callie. The bank’s findings still required formal assessment, yet the records supported what my family had revealed at the café.
I sat staring at the disbursement summary until the truth became painfully simple. My parents had not merely borrowed against the house while I supported it; they had used my identity to make their decision look safer to a lender.
Callie had received the relief, my parents had preserved their image, and I had inherited the risk without being asked. The photograph hadn’t created the betrayal; it had only made me look closely enough to discover it.
Part 5 (THE END)
As the investigation clears my name, my parents face the consequences of their choices, and I discover that peace requires no family permission.
The investigation moved more slowly than my family’s accusations had. A cruel social media post could appear in seconds, but untangling a loan required access records, signed statements, lender reviews, and weeks of letters I read until my eyes hurt.
Nora kept reminding me that my task was to remain accurate, not persuasive. I submitted what I knew, corrected anything I couldn’t prove, and refused to turn the process into revenge.
The more documents arrived, the less room there was for the convenient family story about a misunderstanding. The cash-out money had addressed real arrears, but it had also been used to relieve Callie’s high-interest debts, obligations she’d never mentioned while calling me selfish for protecting my savings.
The lender restricted activity connected to the disputed authorization while its review continued. Nora challenged the attempt to attach liability to me, documented the workplace harassment, and pressed for a written resolution instead of the comforting verbal assurances my mother had always preferred.
Calls from Charleston grew less frequent. Mom’s messages changed from accusations to descriptions of overdue notices, insurance costs, and the embarrassment of neighbors asking why the grass no longer looked perfect.
One message read, “We are going to lose the house, and you could stop it.” I nearly answered out of habit, then reread the phrase and noticed that she still wasn’t asking for forgiveness or admitting what she’d done.
Without my voluntary payments, my parents fell behind. The dispute blocked the simple escape they seemed to expect from using my finances again, and the lender followed its own procedures as the delinquency worsened.
I did not celebrate any of it. That house held my childhood, even the parts I wished had gone differently, and imagining it empty made my throat tighten.
Months later, the foreclosure process had run its course, and the property was bank-owned. I saw it from a rental car during another trip to Charleston: a neglected lawn, a quiet porch, and a sign where Mom’s carefully arranged flowerpots used to be.
I drove past without stopping. The house looked smaller than the one I’d carried in my memory, as though years of guilt had enlarged it into something almost sacred.
I kept driving. Loving a place didn’t require giving its owners the right to take my future.
Not long afterward, Nora forwarded the written outcome of the disputed loan. After examining the available records and my lack of informed authorization, the lender confirmed that I would not be held responsible under the challenged refinance obligation.
I read the letter three times. Then I sat back in my chair and discovered how exhausting it had been to keep expecting the next emergency call.
Owen sent a final confirmation. Daniel accepted my update that the financial dispute had been resolved, and HR’s contact restrictions remained in place should anyone try to revive the spectacle.
Renee took me to coffee at the same little shop where she’d first asked what would happen if I stopped paying. “How do you feel?” she asked.
“Strange,” I admitted. “I thought I’d feel like I won. Mostly I feel tired.”
“You got your choices back,” she said. “That sounds better than winning.”
In February, I moved to Santa Fe. I wanted quieter mornings, a different pace, and a new place where every room didn’t remind me of an argument waiting to happen.
My apartment had high windows, plain walls, and enough sunlight to make the floors glow in the afternoon. I bought used furniture, cooked dinners I actually sat down to eat, and let my bank notifications become boring again.
I kept my accounts private. I didn’t share verification codes, didn’t leave old devices authorized, and didn’t confuse being generous with agreeing to become responsible for another adult’s decisions.
One evening, while unpacking, I found a photograph of the four of us on our Charleston porch. Callie was leaning into the center, Mom was beaming, Dad looked uncertain, and I stood near the edge with one hand in my pocket.
For years I’d seen that picture as evidence that I hadn’t quite earned my place. Now I recognized a boy who had been present all along, whether or not anybody had bothered to make room for him.
I placed the photograph in an envelope instead of throwing it away. I didn’t need to destroy the past; I only needed to stop treating it as instructions for the future.
Mom called once after the bank’s decision. Her voice sounded older, but her first words were familiar: “You didn’t have to let everything fall apart, Evan. We were counting on you.”
I stood at my window, looking toward the pale mountains beyond Santa Fe. I thought about the unanswered birthday calls, the returned anniversary gift, and the signature that had nearly tied my life to a debt I never chose.
“I helped for three years,” I said. “You made decisions without me, and you asked me to carry the consequences. I’m not doing that anymore.”
She waited as though there had to be another sentence, an offer, a promise to fix things. There wasn’t.
I ended the call and set the phone on the table. No one rushed into the room, no alarm sounded, and nothing collapsed around me.
The quiet felt unfamiliar at first, almost like an unfinished task. Then it felt like home, and I understood that the most important thing I’d ever built was a life where love no longer came with an invoice.
THE END