“Your entire lifetime isn’t worth this phone call,” the millionaire sneered across the diner. My $29 waitress uniform clung to my aching shoulders as customers stared, and his untouched eggs cooled beside financial statements he’d left exposed. He laughed when I warned him his company could collapse within six months. By dawn, he was begging outside the diner’s locked door.
PART 1 — THE WAITRESS WHO SAW A MILLION-DOLLAR DISASTER COMING
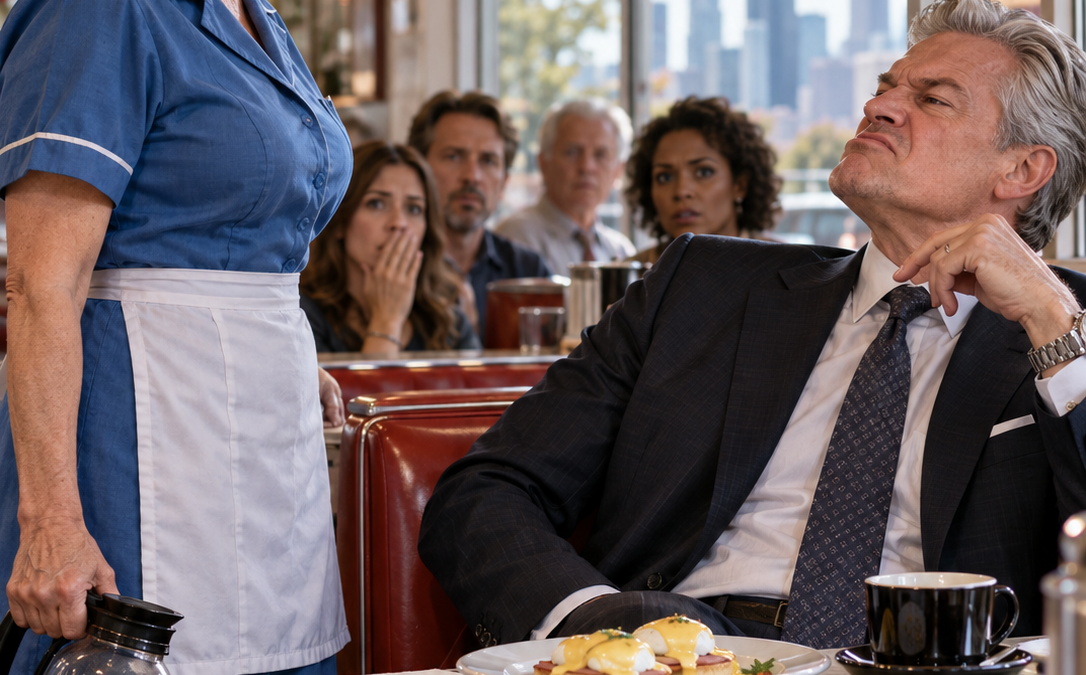
“Do you understand that this phone call is worth more than you’ll make in your entire lifetime?”
The man in the $4,000 suit said it loudly enough for every customer in Murphy’s Diner to hear.
A woman at the counter stopped stirring her coffee. Two construction workers looked up from their breakfast plates.
I stood beside his booth, holding a pot of black coffee, wearing a faded blue waitress uniform that cost $29.99 at Walmart.
My name is Katherine Wells.
I was seventy years old, and two years earlier, I had managed more than $50 million in investment portfolios.
The man insulting me had absolutely no idea.
“Sir,” I said, “I’m simply asking you to take your call off speakerphone. Other people are trying to eat.”
He leaned back in his booth and inspected me with pale blue eyes.
“Then perhaps they should eat somewhere with better clientele.”
One of the construction workers muttered, “Unbelievable.”
The man ignored him.
His phone sat beside a $900 leather briefcase. Financial documents covered the table, surrounding a plate of eggs Benedict he had barely touched.
I could see the company name printed across several pages.
Blackwell Enterprises.
I knew that name.
Harrison Blackwell owned commercial properties in Chicago, invested in technology companies, and regularly appeared in business magazines discussing his latest acquisitions.
He also had a reputation for being an arrogant son of a bitch.
Apparently, the magazines had been accurate about something.
“More coffee?” I asked.
“Obviously.”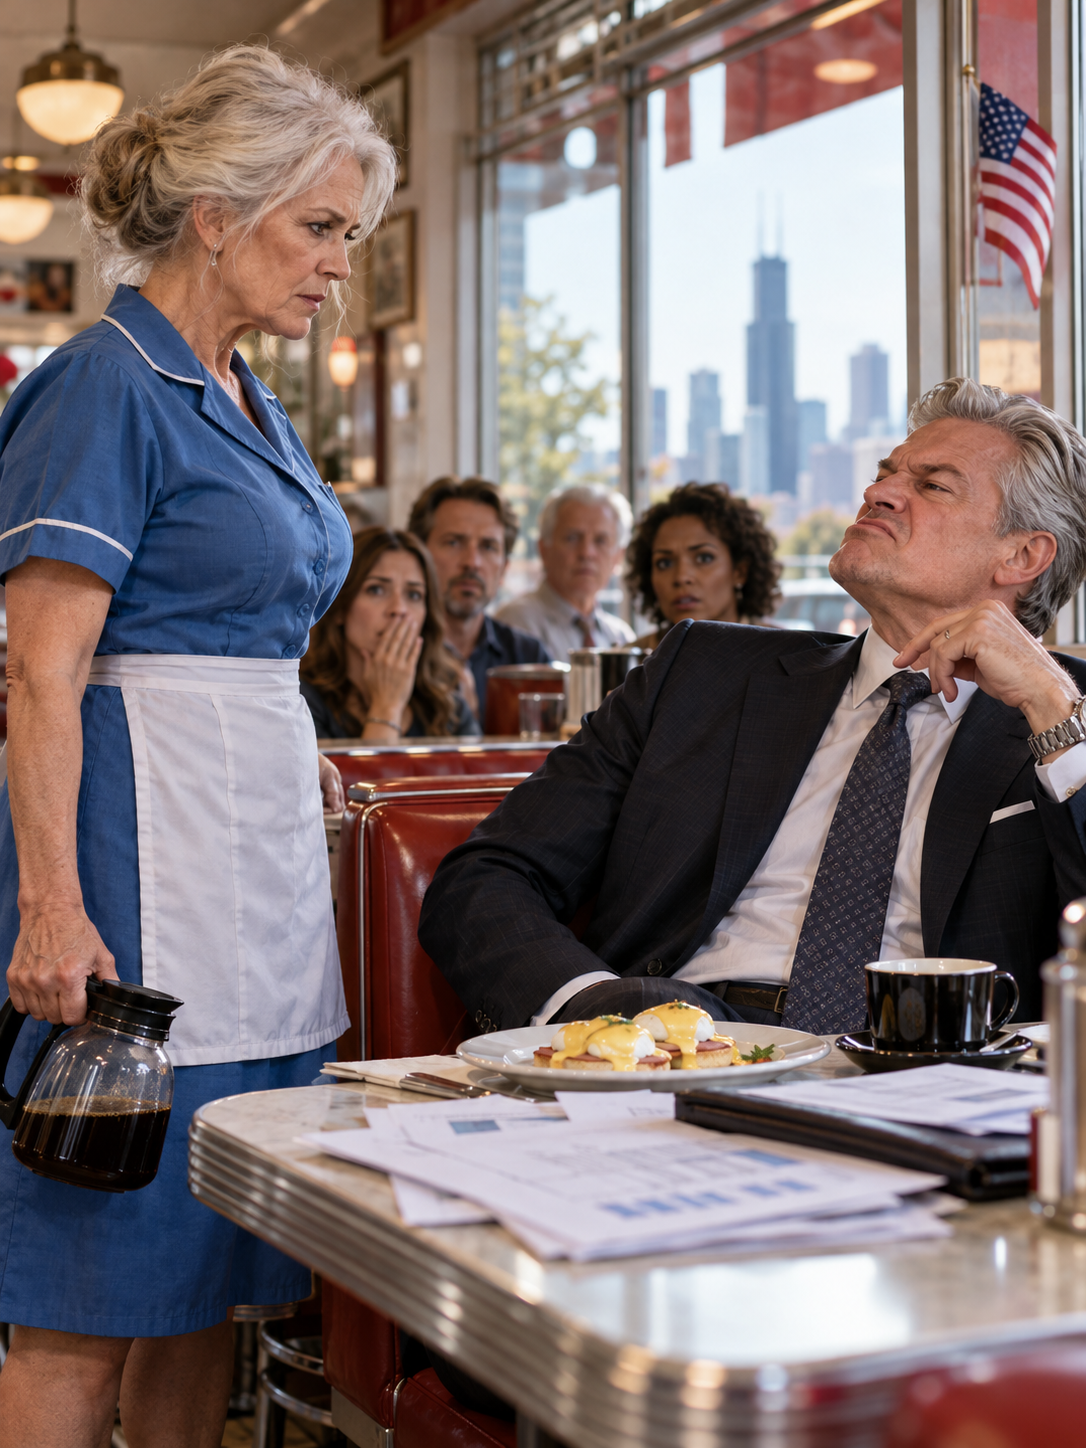
I filled his cup.
Then my eyes caught a line on one of the financial statements.
I looked again.
There was a substantial mismatch between the company’s short-term debt obligations and its projected operating cash flow.
Another document showed a proposed acquisition financed through additional borrowing.
And a third suggested the company was relying on asset valuations that looked suspiciously optimistic.
I hadn’t analyzed a corporate portfolio in nearly two years.
But I hadn’t forgotten how.
“Mr. Blackwell,” I said, “you might want to reconsider that acquisition.”
He stopped scrolling through his phone.
“Excuse me?”
“The one you’re financing with more debt. Based on what I can see, your company already has serious liquidity problems.”
He stared at me.
Then he laughed.
Not a polite laugh.
The loud, dismissive kind men use when they’re certain the person speaking has nothing worth hearing.
“Financial advice from the waitress?”
A couple of customers chuckled awkwardly.
I set down the coffee pot.
“You’re right. You didn’t ask.”
“Glad we agree.”
“But you should probably have someone independently review your leverage and cash flow before your creditors do it for you.”
His expression changed.
“Are you seriously suggesting you understand my company’s financial position?”
“I’m suggesting your numbers are telling a story you don’t seem interested in reading.”
He sat forward.
“Lady, I’ve built companies worth hundreds of millions of dollars.”
“And you’re apparently working very hard to make one of them worthless.”
The construction worker at the counter coughed into his napkin.
Harrison’s face tightened.
“Who the hell do you think you are?”
I looked directly at him.
“Katherine Wells. Former senior partner at Wells and Associates Financial Consulting.”
His eyes narrowed.
I continued.
“Thirty years in financial management. More than fifty million dollars in client portfolios. Corporate restructuring, investment risk, acquisitions, debt management. Pick a category.”
He didn’t respond.
“Now, I haven’t seen your full financial statements, so this isn’t a formal assessment. But if those figures are accurate, you could be facing a serious liquidity crisis within six months.”
For the first time since entering the diner, Harrison Blackwell had nothing clever to say.
Then he gathered his papers.
“I don’t need unsolicited advice from someone carrying a coffee pot.”
“Then don’t leave confidential financial statements spread across a public table.”
He stood.
“You have quite an attitude.”
“It’s complimentary. The eggs Benedict are twelve ninety-five.”
He walked out without paying.
I watched his black Mercedes pull away from the curb.
Tommy Murphy, the diner owner, came out of the kitchen.
“What the hell was that?”
“A customer who doesn’t like hearing bad news.”
“He didn’t pay.”
“Put it on my tab.”
Tommy stared at me.
“You know something, Katherine? For somebody who needs this job, you have a remarkable talent for trying to lose it.”
I picked up Harrison’s untouched plate.
“After what I’ve already lost, Tommy, a twelve-dollar breakfast isn’t going to finish me.”
He didn’t ask what I meant.
He already knew.
Most of Chicago did.
Two years earlier, I had been one of the most respected financial consultants in the city.
My firm occupied an entire floor of a downtown office building. My name was engraved on the glass doors, and clients waited weeks for appointments.
I drove a BMW, owned a beautiful home, and wore tailored suits that cost more than my current monthly rent.
My clients trusted me with retirement funds, family investments, and businesses their parents had spent decades building.
I had earned that trust through thirty years of difficult decisions and long hours.
Then my son destroyed it in eight months.
Michael Wells was thirty-eight when the FBI raided our offices.
It happened on a Tuesday in October.
I was reviewing quarterly reports when federal agents walked through the reception area carrying warrants.
They ordered everyone away from their computers.
An agent handed me a document identifying numerous accounts under investigation.
I recognized every name.
They were my clients.
“What is this?” I asked.
“Ma’am, we need you to step away from your desk.”
Within an hour, I learned that Michael had been forging my signature and transferring client funds through a network of accounts.
He had moved $2.7 million.
Money belonging to people who had trusted me for years.
I called him seventeen times that morning.
He didn’t answer.
By lunchtime, the office was surrounded by reporters.
By dinner, my photograph was on television.
And by the following morning, the headlines had already decided what kind of woman I was.
They used words like Ponzi scheme, betrayal, and financial empire collapse.
My attorneys spent months establishing that I had not authorized the transfers or participated in Michael’s fraud.
The investigators eventually cleared me of criminal wrongdoing.
My clients weren’t particularly interested in that distinction.
They wanted their money.
I didn’t blame them.
A retired school principal confronted me outside a courthouse.
“My husband and I saved that money for forty-two years,” she said.
I had no answer that could make it better.
Legal fees consumed my savings. Lawsuits, frozen assets, and the collapse of my business took nearly everything else.
I sold my house.
Then my car.
Then the jewelry my late mother had left me.
The firm closed, and the reputation I had spent three decades building disappeared with it.
Michael eventually admitted what he’d done.
He offered excuses about investments, pressure, and believing he could replace the money before anyone noticed.
I told him to save those explanations for his attorney.
I loved my son.
That didn’t mean I was going to defend what he had done.
By Christmas, I was sixty-eight years old, with forty-seven dollars in my checking account.
I found a small studio apartment on Chicago’s West Side.
It had one window, a radiator that rattled all night, and neighbors who argued loudly enough that I never needed television.
Then I saw a HELP WANTED sign taped inside Murphy’s Diner.
Tommy interviewed me while flipping hamburger patties.
“You ever waitressed before?”
“No.”
“Can you carry three plates?”
“Probably.”
“Can you deal with rude customers?”
I considered thirty years of dealing with wealthy investors.
“I have extensive experience.”
He hired me.
The job paid enough to cover rent, groceries, and my insulin, provided I worked extra shifts and didn’t miss a day.
During my first week, I dropped an entire tray of breakfast sandwiches.
During my second, I mixed up four orders and received a twenty-cent tip from a man who complained about everything.
By the third month, I could handle a packed breakfast rush without looking at my order pad.
I stayed much longer than I expected.
There were nights I came home with aching feet and wondered how someone who once controlled multimillion-dollar investment decisions had ended up counting quarters for laundry.
But nobody at Murphy’s was asking me to invest their retirement savings.
They wanted coffee, toast, and occasionally an extra side of bacon.
I could deliver those without ruining anybody’s life.
That was enough.
Until Harrison Blackwell walked through the door.
And reminded me that I still knew how to read numbers.
At six the following morning, someone knocked on the diner’s glass door.
We didn’t open until seven.
I was wiping down the counter when I looked up.
Harrison Blackwell stood outside in the rain.
His expensive suit was wrinkled. His silver hair had lost its perfect shape.
He was holding a thick manila folder against his chest.
I unlocked the door.
“We’re closed.”
“I need to speak with you.”
“Breakfast starts in an hour.”
“It’s not about breakfast.”
I stepped aside.
He walked directly to booth seven.
The same booth where he’d humiliated me less than twenty-four hours earlier.
I poured him coffee.
He didn’t complain about the quality.
That was my first indication something had gone very wrong.
“I had my accountants review the numbers you mentioned,” he said.
“And?”
“They found problems.”
“What kind?”
He opened the folder.
“Cash flow shortages. Debt coming due. Obligations that our projected revenue won’t cover.”
I pulled out the chair opposite him.
“How much time?”
He looked down at his hands.
“Four months, according to our latest projections. Maybe less if one of our lenders gets nervous.”
I nodded.
He stared at me.
“You don’t seem surprised.”
“Neither should you. Your documents were advertising the problem across my breakfast table.”
He rubbed his forehead.
“My entire finance department missed it.”
“Or they saw the individual problems and nobody wanted to tell the CEO how they added up.”
“That sounds like an accusation.”
“Then consider it a question worth asking.”
He studied me for a moment.
Then he said something I never expected.
“I need your help.”
I looked at the coffee pot.
“Should I start with a refill?”
“I’m serious.”
“So am I. You look terrible.”
He almost smiled.
“Can you save my company?”
I sat back.
For nearly two years, nobody had asked me a professional question without bringing up Michael.
Now a man who’d treated me like furniture was asking me to rescue his business.
“You have consultants,” I said.
“They’ve helped create this mess.”
“You have accountants.”
“They can’t agree on how bad it is.”
“You have a board of directors.”
“Half of them would like to see me fired.”
“Sounds like you have a complete collection of expensive problems.”
He accepted that without argument.
“I looked you up last night,” he said.
I stiffened.
“I know what happened to your firm.”
“Then you understand why hiring me would be terrible publicity.”
“I understand your son committed fraud.”
“My clients trusted my company. That means I was responsible for protecting them. The fact that I wasn’t involved doesn’t erase what happened.”
“No,” Harrison said. “But it doesn’t mean you’ve forgotten how to do your job.”
I didn’t answer.
He slid the folder toward me.
“Tell me what it takes.”
I opened it.
Twenty minutes later, I understood two things.
First, Harrison Blackwell was in more trouble than his accountants believed.
Second, I was going to help him.
But not cheaply.
“I want my previous consulting rate,” I said.
He raised an eyebrow.
“That’s substantial.”
“So is your problem.”
“What else?”
“A written engagement agreement. Direct access to all relevant financial records. Independent legal review of the arrangement. No restricted documents, no secret accounts, and no surprises.”
“Agreed.”
“I’ll give you recommendations. Your management team and board will make the authorized decisions.”
“Fine.”
“And if we achieve the turnaround targets, I want an equity stake. The terms get negotiated before I begin.”
He looked genuinely startled.
“You want ownership?”
“If I help save the company, I’d like to participate in its future.”
He considered me for several seconds.
Then he extended his hand.
“Have my attorneys draw up the agreement.”
I didn’t shake it immediately.
“One more thing.”
“What?”
“You still owe Tommy twelve ninety-five for yesterday’s eggs Benedict.”
Harrison stared at me.
Then, for the first time, he laughed like a normal human being.
He put a hundred-dollar bill on the table.
“Keep the change.”
“That’s the first sensible financial decision I’ve seen you make.”
Three days later, I walked into Blackwell Tower wearing a navy suit I hadn’t touched in almost two years.
It was a little loose.
I couldn’t afford to have it altered.
Harrison’s office occupied the forty-second floor, overlooking Lake Michigan.
His executive assistant, James, led me into a conference room stacked with financial reports.
He looked at my temporary visitor badge.
“Mr. Blackwell has a very demanding schedule.”
“So do I.”
“He expects results quickly.”
“Then I’m glad he’s paying me to work instead of listening to introductions.”
James stopped talking.
I liked him better that way.
By noon, I had identified the center of the financial crisis.
The Miami real estate project.
Harrison had committed enormous resources to a luxury development whose financing costs were climbing while its expected returns kept shrinking.
Several subsidiaries were consuming cash without producing meaningful revenue.
Meanwhile, the company had increased borrowing to fund acquisitions that looked impressive in investor presentations but produced very little actual cash.
It was the corporate equivalent of using three credit cards to make the minimum payment on a fourth.
The situation was ugly.
But it wasn’t hopeless.
Hidden among the bad decisions were three investment areas producing consistent returns.
A medical technology company.
A clean-energy business.
And a group of smaller technology investments that Harrison rarely mentioned in interviews.
They weren’t glamorous.
They were profitable.
At three, Harrison returned.
He found me standing beside a whiteboard covered in figures.
“How bad?”
“Worse than your accountants told you.”
He loosened his tie.
“That bad?”
“Your Miami project is consuming cash, three subsidiaries need to be sold or wound down, and you’re borrowing against tomorrow’s revenue to pay yesterday’s obligations.”
He shut the conference room door.
“Can we survive?”
“Yes.”
He straightened.
“Thank God.”
“Don’t thank anybody yet. Survival is going to involve selling things you’re emotionally attached to.”
He looked at the whiteboard.
“The Miami development?”
“First on the list.”
“I spent two years promoting that project.”
“And another two years defending it could destroy this company.”
He folded his arms.
“You’re asking me to admit publicly that I made a terrible investment.”
“I’m asking you to stop paying for it.”
He studied the figures.
Then he sighed.
“My board is going to hate this.”
“Excellent. We can all be miserable together.”
Over the next week, I built a restructuring proposal.
We would sell the Miami property to a buyer specializing in distressed developments.
We would liquidate or divest three failing subsidiaries.
Proceeds would reduce debt, while a smaller amount of available capital would support profitable businesses.
Every recommendation came with financial projections, cash-flow scenarios, and an explanation of the alternatives.
When Harrison reviewed the final presentation, he was quiet.
Then he asked, “What if they reject it?”
“Then they’ll need to explain why they prefer insolvency.”
The board meeting took place on a rainy Thursday.
Eleven directors sat around a polished table.
And at the head sat Marcus Webb.
The board chairman.
Fifty-eight years old. Immaculate charcoal suit. Expensive watch.
He had the practiced smile of someone who enjoyed delivering bad news as long as it happened to other people.
Harrison introduced me.
“Katherine Wells, our independent restructuring consultant.”
Marcus looked up from his documents.
“Wells?”
I nodded.
“That’s correct.”
“Interesting.”
He didn’t elaborate.
But he spent the entire presentation watching me more closely than the numbers.
When I finished, he leaned forward.
“You’re recommending we abandon our most prominent investment?”
“I’m recommending we stop financing losses that have no credible path to recovery.”
“That’s a rather aggressive position for an outside consultant.”
“Bankruptcy is also aggressive, Mr. Webb. It tends to upset shareholders.”
A few directors smiled.
Marcus didn’t.
He questioned my assumptions.
I showed him the supporting calculations.
He challenged my valuation of the Miami project.
I produced independent market comparisons.
He suggested Harrison had lost control of the company.
I pointed out that the restructuring plan addressed risks the board had already been informed about.
After ninety minutes, the directors voted.
Five supported the plan.
Four opposed it.
Two abstained.
Under the board’s voting rules, the proposal passed.
Marcus gathered his papers without congratulating Harrison.
As he passed me, he spoke quietly.
“Companies have a way of punishing people who get involved in matters they don’t understand.”
I met his eyes.
“Fortunately, I brought a calculator.”
He walked away.
Harrison waited until the door closed.
“He’s going to come after us.”
“He’s already started.”
And he did.
During the next three weeks, Marcus questioned every transaction.
He demanded emergency updates, contacted major shareholders, and circulated internal concerns about Harrison’s leadership.
He also started quietly encouraging directors to consider replacing the CEO.
Meanwhile, our restructuring began producing results.
The Miami property was sold at a painful but manageable loss.
Three struggling subsidiaries were divested or wound down.
Debt payments were brought back onto schedule.
For the first time in months, the company’s liquidity projections began moving in the right direction.
Harrison looked at the latest report one Friday evening.
“We might actually pull this off.”
“We might,” I said. “If Marcus doesn’t convince everyone to throw the steering wheel out of the car.”
He smiled.
Then he noticed an old photograph beside my laptop.
I’d found it tucked inside a box of archived financing documents he’d asked me to review.
It showed Harrison standing with a dark-haired woman and two children.
He picked it up.
“My wife, Sarah.”
“She was beautiful.”
“She was.”
His thumb moved over the edge of the photograph.
“We lost her and the kids in a car accident fifteen years ago. Drunk driver ran a red light.”
I set down my pen.
“I’m sorry, Harrison.”
He nodded.
“Sarah used to say I spent too much time building a business and not enough time enjoying what we’d already built.”
He looked toward Lake Michigan.
“After they died, I didn’t have much reason to go home.”
That explained something the financial statements couldn’t.
Harrison wasn’t chasing another billion-dollar headline merely because he wanted more money.
His company had become the thing he woke up for.
And now he was terrified of losing it.
“My son is alive,” I said, “but there are days I don’t recognize the man he became.”
Harrison turned.
“Have you spoken to him?”
“Not since he admitted what he did.”
“Do you want to?”
“Some days.”
“And the others?”
“I remember the people who lost their savings.”
He didn’t try to offer advice.
I appreciated that.
For a while, we worked without speaking.
Then Harrison put the photograph inside his desk.
“Marcus is calling another emergency board meeting.”
“When?”
“Next Wednesday.”
I checked our projections.
“Good. We have better figures than we had last time.”
“He wants a vote on removing me.”
“Then we’ll make him explain why he’s trying to fire a CEO whose company is recovering.”
Harrison looked uncertain.
I couldn’t blame him.
Something about Marcus Webb’s behavior bothered me.
He wasn’t acting like a concerned director.
He was acting like a man whose plans were being ruined by the company’s recovery.
And I had seen that pattern before.
The following Tuesday, James rushed into my conference room.
His face was pale.
“Ms. Wells, there are two federal agents downstairs asking for you.”
I stopped typing.
For one terrible moment, I was back in my old office, watching agents carry away boxes of financial records.
“What do they want?”
“They wouldn’t say.”
“Did they produce a warrant?”
“No. They asked to speak with you.”
I stood.
“Where’s Harrison?”
“In his office. He’s asked them to come up.”
When I entered, two agents were waiting.
The older one stood.
“Ms. Wells? I’m Special Agent Martinez. This is Agent Foster.”
I looked at their credentials.
“What can I do for you?”
“We’re investigating a financial fraud conspiracy involving several companies.”
I said nothing.
Agent Martinez continued.
“Your son has been cooperating with federal investigators.”
My fingers tightened around the back of a chair.
“Michael?”
“Yes.”
“What does my son have to do with Blackwell Enterprises?”
Agent Foster opened a folder.
“We have reason to believe the fraud at Wells and Associates was part of a much larger operation.”
I stared at him.
“What larger operation?”
“A group of individuals allegedly arranged financial disruptions at selected businesses, then acquired valuable assets after their market values collapsed.”
Harrison straightened.
“Are you suggesting Katherine’s company was deliberately targeted?”
“Yes,” Agent Martinez said.
I shook my head.
“Michael stole money. He forged my signature. He admitted it.”
“He did,” Agent Foster replied. “But evidence suggests he didn’t develop the scheme alone.”
I couldn’t speak.
Agent Martinez placed a photograph on Harrison’s desk.
It showed Michael sitting across from an older man in an upscale Chicago restaurant.
I recognized the man immediately.
The silver hair.
The expensive suit.
The confident smile.
Marcus Webb.
Agent Martinez watched my reaction.
“Your son identified Mr. Webb as the person who approached him before the fraud began.”
Harrison moved closer to the desk.
“Marcus?”
“Mr. Webb has been under investigation for several months,” Martinez said. “We believe he has used similar methods to undermine businesses and acquire their assets at reduced prices.”
I stared at the photograph of my son.
Then I looked at Harrison.
Marcus had opposed every decision that could save Blackwell Enterprises.
He had been pushing to remove Harrison.
And now the FBI was telling me he had been involved in destroying my company.
Agent Martinez closed the folder.
“Ms. Wells, we have evidence connecting Mr. Webb to your son’s activities. But we believe he’s preparing another move against Blackwell Enterprises.”
Harrison gripped the edge of his desk.
“What do you need from us?”
Martinez looked directly at me.
“We need your cooperation at tomorrow’s board meeting.”
I waited.
Then he explained exactly what they wanted me to do.
And for the first time in two years, I had a chance to face the man who had helped destroy my life.
But getting Marcus Webb into a courtroom would require something far more dangerous than exposing him in a boardroom.
PART 2 — THE MAN WHO DESTROYED MY LIFE NEVER EXPECTED ME TO COME BACK
“Absolutely not.”
That was Harrison’s response when Agent Martinez explained the plan.
“You want Katherine to confront a suspected criminal while wearing a recording device?”
“We’re asking whether she’d be willing to participate in a controlled conversation,” Martinez corrected. “She is under no obligation.”
Harrison looked at me.
“You don’t have to do this.”
I was still staring at the photograph of Michael and Marcus Webb.
For two years, I had believed my son had destroyed my company entirely through his own greed and stupidity.
Now I was learning that someone else had helped him.
Someone who might have benefited from the destruction.
“Tell me everything you know,” I said.
Agent Foster opened another folder.
“Three years ago, Mr. Webb began developing relationships with people inside several financial businesses. We believe he targeted companies whose client portfolios or assets could be acquired at distressed prices.”
“And Michael?”
“Your son was offered money and a financial opportunity in exchange for access to information and assistance in disrupting your firm.”
I leaned back.
“He already had access. I trusted him.”
Neither agent answered.
They didn’t have to.
Foster continued.
“The fraudulent transfers went beyond what was needed to disrupt your firm’s operations. Your son appears to have diverted money for his own benefit as well.”
“So he wasn’t some innocent young man manipulated by a businessman.”
“No, ma’am.”
“Good. I wanted that clear.”
Harrison glanced at me.
I kept looking at Foster.
“Michael knew what he was doing. If you’re telling me another man helped him, I want that man held responsible. But don’t ask me to pretend my son had no choices.”
Martinez nodded.
“We’re not asking you to.”
They had records of communications, financial transfers, and suspicious asset purchases connected to Webb.
Michael had provided additional information while cooperating with investigators.
The FBI had been building the case for months.
But Marcus was careful.
He rarely put his intentions in writing.
And his campaign against Harrison created an opportunity to obtain more evidence about what he intended to do next.
“He wants Harrison removed,” I said.
“We believe so,” Martinez replied.
“Then he’ll push for a forced sale or emergency financing arrangement. Probably through a company he controls indirectly.”
Foster exchanged a glance with Martinez.
“That matches some of what we’ve uncovered.”
I looked at Harrison.
He had gone very still.
“Marcus has been pushing me to accept financing from an outside investment group,” he said.
“Which group?” Martinez asked.
“Northbridge Capital.”
Foster immediately opened his notebook.
“Has he submitted a proposal?”
“Yes. I rejected the initial terms.”
I turned to Harrison.
“Those terms would have given the lender substantial control if you missed certain repayment conditions, wouldn’t they?”
He nodded slowly.
“Potentially.”
I almost laughed.
Not because anything was funny.
Because I finally understood why Marcus had fought so aggressively against our restructuring.
Every dollar of debt we paid down made his proposed financing less attractive.
Every profitable investment we protected made the company harder to acquire cheaply.
We hadn’t just interrupted his plan.
We’d been dismantling it.
“Marcus doesn’t want Blackwell Enterprises to recover,” I said.
“He wants it desperate enough to sell.”
Martinez closed his folder.
“Will you help us?”
I looked at the photograph one last time.
Then I pushed it away.
“Yes.”
The next morning, I arrived at Blackwell Tower before seven.
My attorney had reviewed the proposed cooperation, and I had spoken privately with Agent Martinez about what I was—and wasn’t—comfortable doing.
I wasn’t going to manufacture evidence.
I wasn’t going to accuse Marcus of crimes without a factual basis.
And I wasn’t going to risk another public disaster by improvising a dramatic confrontation.
My role was simple.
Attend the meeting.
Present the company’s financial position.
If Marcus approached me privately, allow him to speak.
Ask direct questions.
Let him decide what to say.
The agents already had substantial evidence and were working through the legal steps needed for their case.
My cooperation could help establish his intentions toward Blackwell Enterprises.
Harrison met me outside the conference room.
He was holding two Starbucks cups.
“Black coffee,” he said, handing me one.
“Trying to buy my loyalty?”
“Is it working?”
“Depends. Did you keep the receipt?”
He smiled.
Then his expression turned serious.
“I should have listened to you the first morning.”
“Yes.”
“I was an arrogant jackass.”
“Yes.”
“You could pretend to disagree.”
“I could. But you specifically hired me for my honesty.”
He looked down at his coffee.
“If anything feels wrong today, you walk out. Forget the company.”
I examined his face.
Six weeks earlier, this man had told me his phone call was worth more than my lifetime earnings.
Now he was prepared to lose his business rather than put me under unnecessary pressure.
“You’ve changed, Harrison.”
“Bankruptcy projections tend to improve a man’s personality.”
I laughed.
Then I adjusted my jacket.
“Let’s go disappoint Marcus Webb.”
The emergency board meeting began at ten.
Marcus arrived carrying a leather portfolio and wearing a smile that suggested he had already decided the outcome.
He shook hands with several directors.
He didn’t acknowledge me.
That was fine.
I preferred being underestimated.
Harrison sat at the head of the conference table.
I took the chair to his right.
James distributed updated financial statements while Marcus reviewed his notes.
“Ladies and gentlemen,” Marcus began, “I wish we were meeting under better circumstances.”
He paused.
“This company has experienced unacceptable volatility under Mr. Blackwell’s leadership.”
He spent fifteen minutes discussing declining asset values, failed acquisitions, and concerns from investors.
He conveniently ignored the improving cash flow.
He also failed to mention that he’d approved several of the investments he was now criticizing.
When he finished, Harrison leaned forward.
“Marcus, the company has improved its cash position significantly since the last meeting.”
“Temporary improvements,” Marcus replied.
“Supported by verified transactions,” I said.
He turned toward me.
“Ms. Wells, I’m sure you believe your work has been valuable.”
“I do. Fortunately, the financial statements agree.”
A director near the window smiled.
Marcus tapped his pen against the table.
“Your restructuring has also caused substantial realized losses.”
“Yes,” I answered. “Selling an unsuccessful investment creates a realized loss. Keeping it while financing charges accumulate creates a larger problem.”
“You’re oversimplifying.”
“Then let’s use the actual numbers.”
I connected my laptop to the screen.
The first chart showed the company’s short-term debt obligations before our restructuring.
The second showed the current position.
The third showed operating cash flow.
Every improvement came with supporting documentation.
Marcus stopped tapping his pen.
I moved to the next slide.
“Blackwell Enterprises is not out of danger. But its operating businesses are stabilizing, its immediate debt burden has been reduced, and its remaining investments are producing stronger returns.”
One director leaned toward Marcus.
“These figures are considerably better than what you described in your letter.”
Marcus cleared his throat.
“Financial projections can be manipulated.”
“Correct,” I said. “Which is why I’ve included bank confirmations, executed sale agreements, and independently reviewed financial information.”
He stared at the screen.
Then he changed tactics.
“Perhaps we should discuss the consultant responsible for these recommendations.”
Harrison stiffened.
Marcus looked around the table.
“Some of you may recognize the name Katherine Wells.”
I kept my hands folded.
“Her former company was involved in a multimillion-dollar fraud scandal.”
A director frowned.
“I remember that case.”
“Of course you do,” Marcus said. “It was extensively covered in the financial press.”
He turned toward me.
“Tell us, Ms. Wells. Why exactly did your previous company close?”
Harrison started to speak.
I raised one hand.
“I’ll answer.”
Marcus leaned back.
“My son forged my signature, stole $2.7 million in client funds, and destroyed the business I’d spent thirty years building.”
The room became quiet.
“Federal investigators found no criminal wrongdoing on my part. My firm’s collapse was devastating to our clients, and I remain deeply sorry for what they suffered.”
I looked directly at Marcus.
“Those are facts. I won’t conceal them.”
His smile slipped.
“Yet you expect this board to trust your financial judgment?”
“I expect this board to examine the evidence supporting my recommendations.”
I clicked to the next slide.
“Now, if you’d like to discuss financial judgment, Mr. Webb, perhaps you can explain why you’ve repeatedly supported an emergency financing proposal that would expose this company to substantially greater risk.”
He sat forward.
“That proposal provides liquidity.”
“At a very expensive price.”
“Temporary sacrifices are sometimes necessary.”
“Then why are you recommending those sacrifices now, when our existing restructuring is reducing the need for outside financing?”
He didn’t answer immediately.
Harrison watched him.
So did the other directors.
Marcus finally said, “I’m protecting shareholder value.”
“Then we share an objective.”
I closed my laptop.
“Because selling a recovering company at a distressed valuation would be a terrible way to protect its shareholders.”
Marcus stood.
“I suggest a brief recess.”
Nobody objected.
He walked out through the side door.
I waited a moment before following.
Marcus was standing near the windows in a smaller conference room when I entered.
He turned.
“Well,” he said. “That was quite a performance.”
“Thank you.”
“Don’t mistake a few favorable projections for a victory.”
“I haven’t.”
He crossed his arms.
“You know, I finally remembered where I’d heard your name.”
“I imagine the newspaper articles helped.”
“No. Before that.”
I said nothing.
He walked toward the conference table.
“Wells and Associates had an impressive client portfolio. Very valuable relationships.”
“Relationships my clients spent years trusting me to protect.”
“Trust is an expensive commodity.”
I looked at him.
“Is that what you told Michael?”
His expression changed.
Only slightly.
But I saw it.
“Your son was an adult,” he said.
“I know.”
“He made his own decisions.”
“I know that too.”
Marcus studied me.
“Then perhaps you should stop looking for someone else to blame.”
I moved closer to the table, keeping my distance from him.
“I’m not looking for someone to blame for Michael’s choices. I’m trying to understand why a man on Harrison’s board would have had any interest in my firm’s collapse.”
He smiled.
“You think rather highly of yourself.”
“Not particularly. But my client list was valuable, wasn’t it?”
He didn’t answer.
“And after the scandal, several of those client relationships and business assets became available at distressed prices.”
“That’s how markets work, Katherine.”
“Markets don’t normally require forged signatures.”
His jaw tightened.
“Be careful.”
“About what?”
“Making accusations you can’t substantiate.”
I held his gaze.
“Then help me understand something. Why would Michael have met with you before the fraud began?”
For the first time, Marcus looked genuinely unsettled.
“Michael talked to a lot of people.”
“Did he?”
“He was ambitious. Frustrated. He wanted to be successful without waiting another twenty years to inherit your business.”
The wording caught my attention.
“Inherit?”
“Don’t pretend you didn’t know he wanted more responsibility.”
“He already had responsibilities. He abused them.”
Marcus exhaled.
“He was offered an opportunity.”
“By whom?”
Marcus looked toward the door.
Then back at me.
“You really don’t know when to stop, do you?”
“Not when I’m asking a reasonable question.”
He lowered his voice.
“I made introductions. I showed him options for moving business relationships into a different structure. He was supposed to understand the difference between an opportunity and stealing money.”
I kept my face neutral.
“An opportunity that depended on my firm getting into financial trouble?”
His silence lasted several seconds.
Then he shrugged.
“Your company was vulnerable. Michael made it considerably more vulnerable than anyone anticipated.”
There it was.
Not a grand confession.
Not a villain delivering a rehearsed speech.
But an acknowledgment that Marcus had been involved with Michael before the collapse, and that the outcome had gone beyond what he’d anticipated.
I let him continue.
“Frankly, I expected you to be more practical afterward,” he said. “You could have sold the remaining business relationships, walked away with something, and spared yourself all that public embarrassment.”
“And now you’re offering Harrison the same kind of solution?”
Marcus smiled again.
“Harrison has an emotional attachment to a business he’s no longer equipped to manage.”
“And Northbridge Capital is prepared to relieve him of it?”
“The terms are reasonable.”
“For Northbridge.”
“For people who understand leverage.”
I nodded slowly.
“People like you?”
His eyes hardened.
“I’ve spent twenty-five years turning distressed assets into profitable investments.”
“Then you must be furious that Blackwell Enterprises is no longer quite so distressed.”
He stepped closer.
“You think Harrison is going to protect you when this falls apart?”
I didn’t move.
“He’s a businessman, Katherine. Businessmen protect themselves.”
“And you?”
“I make sure I’m on the winning side.”
I looked toward the door.
For years, I’d imagined confronting whoever had helped destroy my company.
I’d expected anger.
Instead, I found myself looking at a middle-aged man with excellent tailoring and a very ordinary appetite for other people’s money.
“You should return to the meeting, Marcus.”
He frowned.
“Excuse me?”
“The directors are waiting.”
I turned and walked out.
I didn’t look back.
When the meeting resumed, Marcus appeared irritated.
He sat down and immediately called for a vote of no confidence in Harrison’s leadership.
Before the motion could proceed, one director raised a question.
“Marcus, can you clarify your relationship with Northbridge Capital?”
Marcus stared at him.
“What relationship?”
“You’ve recommended their financing proposal several times. I’d like to understand whether you have any financial interest in the transaction.”
“I’ve made all required disclosures.”
Another director spoke.
“Then providing confirmation shouldn’t be difficult.”
Marcus looked around the table.
For the first time that morning, he seemed to realize the room wasn’t entirely on his side.
Harrison leaned forward.
“I also believe the board needs an independent review of the financing proposal and any potential conflicts of interest.”
Marcus slammed his portfolio shut.
“This is ridiculous.”
I watched him.
His attention shifted to the conference room doors.
Then to me.
Something in his expression changed.
“You,” he said quietly.
I didn’t answer.
He stood.
“What have you done?”
Before anyone could respond, the doors opened.
Agent Martinez entered with Agent Foster and several other federal agents.
“Marcus Webb?”
Marcus went rigid.
“Who’s asking?”
“Special Agent Martinez, FBI.”
Harrison remained seated.
I folded my hands on the table.
Martinez approached Marcus and identified himself again.
“Mr. Webb, we have a federal arrest warrant.”
One of the directors whispered, “Jesus Christ.”
Marcus stared at me.
“You set me up.”
“No,” I said. “You made your own decisions.”
The agents took him into custody.
His attorney would later challenge parts of the government’s case, including the interpretation of his recorded statements.
But the recording wasn’t the whole case.
Investigators already had records connecting him to suspicious transactions, communications, and acquisitions.
His conversation with me had given them additional evidence about his involvement with Michael and his intentions toward Blackwell Enterprises.
As Marcus was escorted from the room, he turned back.
“Katherine, you have no idea what you’re doing.”
I stood.
“Marcus, that’s exactly what you thought the first time.”
He said nothing else.
The doors closed behind him.
For several seconds, nobody moved.
Then James, who had been standing beside the wall, looked at Harrison.
“Sir,” he asked carefully, “should I cancel the remainder of the agenda?”
Harrison let out a breath.
“Yes, James.”
He looked at me.
“I think we’ve accomplished enough for one morning.”
The arrest didn’t instantly fix everything.
There were lawyers.
Investigators.
Shareholders demanding explanations.
Federal authorities requesting documents from multiple businesses.
Marcus’s allies on the board suddenly developed an extraordinary enthusiasm for transparency.
Some directors resigned.
Others cooperated with the investigation.
The company launched an independent review of prior financing proposals and potential conflicts of interest.
Harrison spent weeks answering questions from lenders and investors.
I spent nearly as much time working with auditors as I did preparing financial projections.
But something had changed.
We were no longer fighting a board chairman who seemed determined to sabotage every attempt at recovery.
For the first time, the company’s leadership could concentrate on the actual business.
The restructuring continued.
Debt came down.
Cash flow improved.
Several investments performed better than expected.
The Miami disaster remained a loss, but it was a closed loss.
We were no longer pouring good money into a project that couldn’t support itself.
Six weeks after Marcus’s arrest, Harrison walked into my office with an updated financial report.
He placed it on my desk.
I opened it.
Then I checked the numbers again.
“Our operating cash flow is positive.”
“It is.”
“And we have sufficient liquidity to meet our near-term obligations?”
“We do.”
I looked up.
“Harrison, we’re not out of the woods.”
“I know.”
“We still have substantial work ahead.”
“I know that too.”
He smiled.
“But we’re going to survive.”
I looked at the report.
Then I looked at him.
For nearly two years, I’d been unable to open financial statements without remembering the offices I’d lost.
Now I was sitting on the forty-second floor of a Chicago office building, looking at numbers that represented a company recovering because of decisions I’d helped make.
I hadn’t lost my ability.
I’d lost the opportunity to use it.
And I finally had that back.
Two months after the arrest, Michael asked to see me.
His attorney contacted mine.
I almost refused.
Then I remembered the photograph on Harrison’s desk.
Sarah.
His children.
The family he would never have another conversation with.
My son was alive.
And while that didn’t erase what he’d done, I wanted to hear what he had to say.
I met Michael in a federal detention facility where he was being held while his case continued.
He looked older.
His hair was shorter. His cheeks were thinner.
For a moment, I saw the little boy who used to sit at my kitchen table doing multiplication problems while I worked through client reports.
Then he sat down across from me.
“Hi, Mom.”
“Michael.”
He swallowed.
“I heard about Webb.”
“I imagine you did.”
“I didn’t know everything he was planning.”
I watched him carefully.
“Did you know enough to understand what you were doing to my clients?”
He lowered his eyes.
“Yes.”
“Did you know that people could lose their retirement savings?”
“Yes.”
“Then don’t start by telling me how Marcus manipulated you.”
He nodded.
“I know.”
For several minutes, he struggled to speak.
Then he said, “I thought I could make more money. I thought if I had control of the accounts, I could replace what I took before anyone noticed.”
“And when you realized you couldn’t?”
“I kept going.”
I waited.
“I was afraid you’d find out.”
I looked at him.
“You were afraid I’d be disappointed in you.”
He nodded.
“And instead, you let hundreds of people become collateral damage.”
He covered his face.
“I’m sorry.”
I believed he was sorry.
I also knew that being sorry after getting caught was not the same thing as choosing to stop before anyone got hurt.
“Do you know how I paid rent after the company collapsed?” I asked.
He shook his head.
“I worked at a diner.”
He stared at me.
“I served breakfast, cleaned tables, and took home cash tips. Some nights I had to choose which bills could wait.”
“Mom, I—”
“I’m not telling you because I want your pity.”
I leaned forward.
“I’m telling you because when you forged my signature, you took more than money. You took my ability to look clients in the eye and promise their savings were safe.”
He began crying quietly.
I didn’t comfort him.
Not because I didn’t love him.
Because he needed to sit with what he’d done.
“I’ll cooperate with everything,” he said.
“Good.”
“I’ll help recover whatever money I can.”
“Better.”
He looked at me.
“Will you ever forgive me?”
I considered the question.
“I don’t know.”
He nodded.
It was the only answer I had.
“But I do know this,” I continued. “If you want a relationship with me someday, it won’t be built on excuses. You’ll have to take responsibility and keep taking it, even when nobody’s watching.”
He wiped his face.
“I understand.”
I hoped he did.
When the visit ended, I walked outside and stood beside my car.
For the first time in two years, I hadn’t needed to defend my son or defend myself.
I had simply told him the truth.
That was enough for one day.
Six months after Marcus Webb’s arrest, Blackwell Enterprises was in a dramatically stronger position.
The remaining company debt was manageable.
Operating revenue had stabilized.
The profitable investments we’d protected were expanding.
Harrison had also agreed to strengthen internal financial controls and reduce the concentration of authority that had allowed poor decisions to go unchallenged.
He no longer treated dissent as disrespect.
That improvement alone was worth a considerable amount of money.
My consulting business was growing too.
Wells Strategic Consulting had a waiting list.
A manufacturing company in Ohio wanted help restructuring its debt.
A family-owned logistics business in Wisconsin needed an independent assessment.
A Chicago technology firm wanted someone to review its acquisition strategy before signing a nine-figure agreement.
Companies that once might have refused to take my calls were asking for meetings.
My name was appearing in business publications again.
This time, the articles described corporate recovery and financial expertise.
The investigation into Marcus’s activities also helped establish the full circumstances surrounding the collapse of my former company.
Insurance recoveries, settlements, and funds recovered through the legal process eventually returned a substantial portion of the money my former clients had lost.
Not everyone was made completely whole.
And no payment could restore the years of anxiety they’d endured.
But several people I’d been afraid to approach reached out.
One was the retired school principal who had confronted me outside the courthouse.
She called my office on a Wednesday afternoon.
“Katherine Wells?”
“Yes.”
“This is Margaret Collins.”
I recognized her voice immediately.
“Mrs. Collins.”
“I received another recovery payment this week.”
“I’m glad.”
She paused.
“I wanted you to know something.”
I waited.
“I believed you were responsible for everything.”
I looked down at my desk.
“I understand.”
“I was wrong about your involvement. I’m sorry for the things I said to you.”
I closed my eyes briefly.
“Mrs. Collins, you lost money you and your husband worked your whole lives to save. You were entitled to be angry.”
“Yes,” she said. “But I should have been angry at the right people.”
After the call ended, I remained at my desk for a long time.
Harrison found me there.
“Everything okay?”
I nodded.
“An old client.”
“Good news?”
“Some of the best I’ve had in years.”
He didn’t press.
Instead, he placed an envelope in front of me.
“What is this?”
“Your finalized equity agreement.”
I opened it.
The terms we’d negotiated at the beginning of our partnership had been satisfied.
I now owned a meaningful minority stake in the business I’d helped rescue.
I read the document twice.
Then I looked at Harrison.
“You actually followed through.”
He pretended to be offended.
“Were you expecting me to break our agreement?”
“I’ve worked with wealthy businessmen for thirty years. My expectations are appropriately cautious.”
He laughed.
Then he became serious.
“Katherine, you saved this company.”
“No. We saved it. You were willing to make decisions most CEOs would have been too proud to consider.”
“I needed someone who wasn’t afraid to tell me I was wrong.”
“You made that part surprisingly easy.”
He shook his head.
“Do you ever stop?”
“Only when the billable hours run out.”
The following Friday, Harrison asked me to breakfast.
“There’s somewhere I want to take you,” he said.
“Am I supposed to be impressed?”
“Probably not.”
At eight the next morning, his Mercedes pulled up outside Murphy’s Diner.
I looked at him.
“Seriously?”
“Absolutely.”
We walked inside.
Tommy was behind the counter, arguing with a supplier over the phone.
When he saw me, he nearly dropped the receiver.
“Katherine?”
“Morning, Tommy.”
He looked from me to Harrison.
Then back to me.
“Well, I’ll be damned.”
I smiled.
“Business slow?”
“Same as always. Everyone wants cheap coffee and nobody wants to pay for extra bacon.”
He came around the counter.
I’d never seen Tommy in anything other than a grease-stained apron.
He hugged me anyway.
“Look at you,” he said. “Fancy suit. Fancy friend. Don’t tell me you finally found somebody rich enough to pay for breakfast.”
Harrison extended his hand.
“Harrison Blackwell.”
Tommy looked at him.
His eyes widened.
“Wait a minute. You’re the guy who walked out on his eggs Benedict.”
“I believe I’ve settled that account.”
“With a hundred-dollar bill.”
“Then I hope my credit is still good.”
Tommy grinned.
“For you two? Booth seven.”
We sat down.
The vinyl upholstery still had the same cracks.
The coffee still tasted terrible.
The fluorescent lights still made everyone look like they needed a vacation.
And I was happier sitting there than I’d been in some of the finest restaurants in Chicago.
Tommy brought us two menus.
“You ordering the usual, Katherine?”
“Scrambled eggs, whole-wheat toast, and black coffee.”
He looked at Harrison.
“And you, Mr. Big Shot?”
Harrison studied the menu.
“Eggs Benedict.”
Tommy laughed.
“Of course.”
When he left, Harrison leaned back in the booth.
“Do you remember what you told me the first time we met?”
“That you were about to bankrupt your company?”
“Besides that.”
“That you needed to lower your voice?”
He smiled.
“You told me my numbers were telling a story I didn’t want to read.”
“They were.”
“I thought you were just a bitter old woman who wanted to embarrass me.”
I raised an eyebrow.
“Careful. You’re dangerously close to ruining breakfast again.”
He laughed.
“I’m serious. I walked into this place believing my money made me the most important person in the room.”
“And now?”
He glanced toward Tommy, who was refilling coffee for a construction worker.
“Now I think I was probably the least useful person in it.”
I stirred my coffee.
“That might be a little harsh.”
“You told me you’d stop my company from collapsing. You did. Tommy kept a business running through every bad year Chicago could throw at him.”
He looked around.
“And I couldn’t even make a phone call without being an ass.”
“Personal growth,” I said. “Very encouraging at your age.”
He shook his head.
Then his expression softened.
“I’m glad you didn’t let me chase you away.”
I looked at the waitress carrying plates past our booth.
She was about twenty-five, with tired eyes and a pencil tucked behind one ear.
A customer near the door snapped his fingers at her.
She turned.
“Just a moment, sir.”
He snapped again.
Before I could say anything, Harrison stood.
“Excuse me,” he told the customer. “She heard you the first time.”
The man looked startled.
Harrison sat down.
I stared at him.
“What?” he asked.
“Nothing.”
“You’re smiling.”
“Am I?”
“Yes.”
I picked up my coffee.
“Must be the excellent service.”
That afternoon, I returned to my office.
Not a rented cubicle.
Not a corner of someone else’s conference room.
My own office.
The name on the glass door read:
Katherine Wells — Wells Strategic Consulting.
My desk held three new client files.
My calendar was full.
My checking account had more money than I’d earned during my final year at Murphy’s.
But the most valuable thing on that desk wasn’t financial.
It was a small photograph Tommy had given me when I left the diner.
In it, I was standing behind the counter wearing my blue uniform, holding a coffee pot, laughing at something one of the regulars had said.
I’d once been embarrassed by that photograph.
I thought it represented the lowest point of my life.
Now I saw it differently.
The woman in that picture had lost her business, her home, and most of her savings.
Her son had betrayed her.
Her reputation had been destroyed in public.
And she still got up at five every morning, caught the bus to work, and did the job in front of her.
She hadn’t known whether she’d ever work in finance again.
She just kept going.
I put the photograph beside my computer.
Then I opened the first client file.
It belonged to a small manufacturing company facing serious debt problems.
Their owner had attached a handwritten note to the documents.
Ms. Wells, someone recommended you because you tell people the truth, even when they don’t want to hear it. We need that right now.
I smiled.
Then I picked up the phone.
“This is Katherine Wells,” I said. “I’ve reviewed your preliminary financial statements, and I think we need to have a conversation.”
The owner sounded nervous.
“Is it bad?”
“Not as bad as you think. But there are some decisions you’re going to have to make.”
He exhaled.
“Can you help us?”
I looked out at the Chicago skyline.
Two years earlier, I had been standing behind a diner counter while a wealthy man laughed at the idea of taking financial advice from a waitress.
Now I owned a consulting business again.
I had helped save a company.
I’d uncovered the man who had participated in destroying mine.
And I’d learned something I should have understood long before my first million-dollar client walked through the door.
A person’s job title tells you what they do.
It doesn’t tell you what they know.
Their bank balance tells you what they have.
It doesn’t tell you what they’re worth.
And losing everything doesn’t mean you’ve lost the ability to begin again.
I turned back to the phone.
“Yes,” I told the owner. “I believe I can help.”
Then I opened a fresh spreadsheet.
And got to work.
THE END