I Hid $2.5 Billion When I Got Married And I Was Right! The Next Morning, MIL Showed Up With A Lawyer
Chapter 1: Fourteen Hours After Our Wedding, His Mother Demanded My Signature
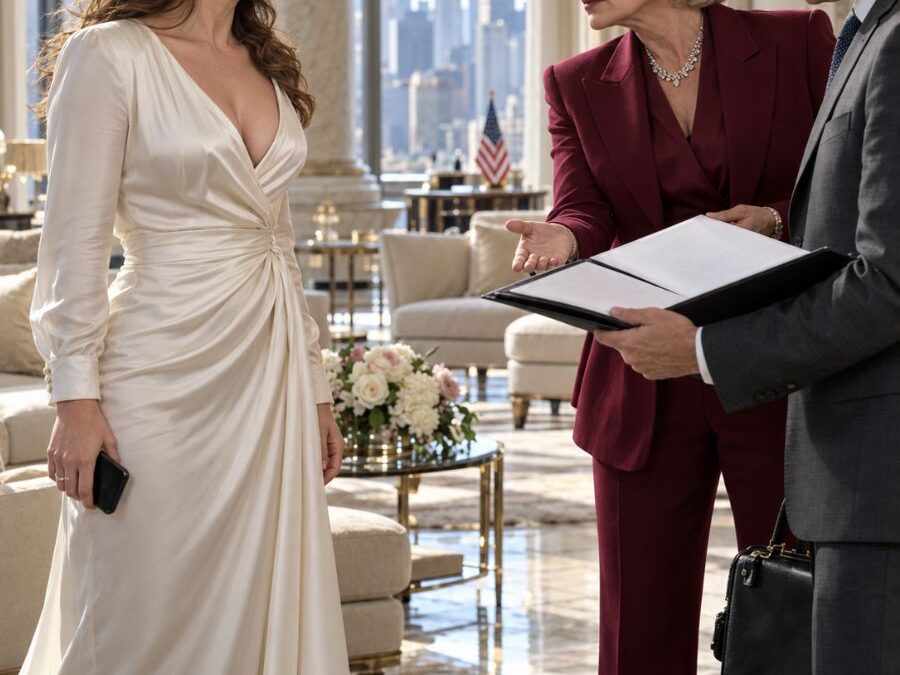
At 8:15 the morning after my wedding, my new mother-in-law walked into our hotel suite with a notary and a thick folder—and told me to sign before we left for our honeymoon. What could possibly be so urgent that it couldn’t wait? Only fourteen hours earlier, Liam and I had cut our wedding cake while our families toasted our future. Now I stood in my bathrobe beside a cup of cold coffee as Brenda set the papers beside my half-eaten croissant.
“Just basic financial housekeeping,” she said, clicking a blue pen open. The cover read Mixed Asset Management Authorization. The car was waiting downstairs, she reminded me, and we’d miss traffic if we delayed. The notary wore a state-issued lanyard and checked her watch as though she had other appointments. The folder looked thirty pages thick. Liam emerged from the shower, saw his mother, and looked genuinely surprised, but when she explained that I was hesitating, he slipped a damp hand onto my shoulder.
“It’s standard stuff, babe,” he said in the soothing voice he used to close real-estate deals. “Mom’s accountant found some tax loopholes. It’ll help me manage your little fund.” The phrase landed harder than he realized. Before our wedding, my trust attorney, Sarah, had drafted a strict prenuptial agreement. Liam had signed without negotiation, insisting he loved me, not my money. He knew I’d inherited something, but my old Toyota, ordinary clothes, and corporate job had clearly shaped his assumptions. The prenup named Apex Holdings but never disclosed the trust’s current valuation.
I didn’t touch the pen. Instead, I put its cap back on, dropped it into Brenda’s open purse, and slid the folder into my carry-on. “I’ll have Sarah review it when we land in Costa Rica. If she approves, I’ll sign and send it back.” Brenda’s warmth vanished. Liam accused me of treating his mother like a scammer and ruining our first morning as husband and wife. He turned away as if I’d embarrassed him, making my caution look like a personal insult. I zipped the suitcase. “If it’s only tax paperwork, it can wait until Tuesday.”
For twelve days, Liam played the devoted newlywed perfectly—room service, boat tours, sunscreen on my shoulders—and never mentioned the folder again. I watched and waited. After we returned to Charlotte, I was paying our electricity bill on Liam’s unlocked tablet when his email appeared on the screen. I wasn’t snooping; his inbox was already open in Safari. A broker named Vance had sent an urgent margin-call notice: Liam’s stalled development needed $145,000 by the fifteenth or face liquidation. Beneath it was Brenda’s reply: “You have to force her to sign that authorization before the fifteenth. If you don’t cover the margin, the bank will foreclose on my house.” In one instant, the hotel-room scene made sense: this was no tax cleanup. It was a rescue mission.
Chapter 2: One Email Revealed The Debt Behind His Perfect Marriage Proposal
I photographed the email chain, making sure the date, addresses, amount, and Brenda’s exact words were legible, then paid the electricity bill and left the tablet exactly where I’d found it. Liam came in from the garage whistling, and I smiled while stirring the pasta sauce. Then I began checking facts. As a risk analyst, I knew not to confront a desperate debtor before securing my own position.
The public records told a worse story. Liam’s commercial loan had been downgraded to subprime months earlier, and a notice of default had been filed on October 12. I checked my calendar: three days later, on a weekend in Charleston, he had proposed beneath an enormous oak near the Battery, with a hidden photographer ready to capture the moment. I remembered him saying I was the missing piece of his puzzle and that he loved my independence. Now those words sounded like a financial appraisal. He had proposed seventy-two hours after his project officially collapsed.
Two hundred thousand dollars sat in our joint savings account. I had transferred it just before the wedding after Liam suggested we create a cash fund for a future home in Myers Park. It matched the margin call almost too neatly, leaving a $55,000 cushion for fees and interest. Then I found public records showing Brenda had taken out a large second mortgage on her SouthPark home to prop up her son’s failing project. They had risked her roof, then found a wife they thought could rescue them.
I sent Sarah the folder’s scan. She confirmed that my grandfather’s trust was protected by the prenup; Liam couldn’t touch its capital, dividends, or voting shares. But the authorization was far from harmless: it would let Liam drain the joint savings without my signature and use my future salary as collateral for commercial debt. “If you’d signed that morning, he could have moved the money by noon,” she said. Her advice was simple: don’t confront him yet. I froze my credit at all three bureaus, wrote the temporary unfreeze PIN on a note hidden inside my desk lamp, and changed the joint account’s transfer settings so anything over $1,000 required biometric approval through the authenticator on my phone.
At Sunday dinner at Brenda’s house, four days before the deadline, she and Liam tried another approach. Over pot roast and wine, she said separate lawyers built walls between spouses; Liam covered my hand and said he felt like he’d married a business partner. I calmly explained that marriage was an economic partnership under North Carolina law, and Sarah was doing due diligence. Brenda’s soft, wounded expression hardened. “You’re entirely too calculating,” she snapped. “I’m a risk analyst,” I said, returning to my meal. They stopped asking about the paperwork, but the deadline kept closing in.
Chapter 3: I Quietly Secured Our Savings Before They Could Steal Everything
On Thursday night, the day before the deadline, Liam barely touched his takeout dinner. His phone vibrated again and again on the marble island, but he pretended not to notice. I told him I was going to shower and left my iPad on the living-room table, just as I usually did. He knew the passcode, the year we’d met combined with my birth month. I kept my Apple Watch on beneath the spray.
Eight minutes later, two sharp vibrations tapped my wrist. I cleared the water lock and read the alert: an outbound wire transfer for $145,000 to Hawthorne Commercial Equity LLC was pending secondary biometric authentication. Liam had used the trusted iPad to access our joint account and initiate the exact transfer his mother had been pushing me to authorize. My new security threshold had stopped the money at the final gate, leaving it in a holding queue until my phone approved it.
I turned off the shower and went downstairs. Liam sat on the sofa watching baseball, the iPad resting where I’d left it. His shoulders had relaxed; he looked like a man who believed he’d escaped a disaster. “Water hot enough?” he asked. “Perfect,” I said, and he smiled as if nothing had happened. I didn’t approve the transfer or alert him. Instead, I waited for the bank to call, knowing that a quiet cancellation would let him pretend it had all been a misunderstanding.
At 2:15 Friday afternoon, Bank of America’s fraud department confirmed the transaction was still frozen and asked whether I had authorized it. The representative explained that the wire had come through a recognized device on our home network but had been halted by the threshold I’d set. I could have cancelled it quietly and let Liam claim it was a mistake. Instead, I told the representative plainly that I had not authorized the transfer and that my husband had been in possession of the device. The bank cancelled the wire, locked the joint savings, and opened a formal suspected-fraud investigation. The funds would remain inaccessible while it reviewed the case.
That evening, Liam arrived home carrying white hydrangeas and announced he’d booked a celebratory dinner at Fahrenheit, an expensive rooftop restaurant in Uptown Charlotte. He ordered steak and a $300 bottle of Silver Oak Cabernet, then toasted “our future,” claiming his project’s financing was finally secure. Brenda texted to ask whether the broker had confirmed the wire. Liam hid his phone in his lap to answer her, then raised his glass and smiled at me. I touched my water glass to his. He believed he’d saved his project. I knew the bank had made a record he couldn’t charm his way out of.
Chapter 4: His Fraud Alert Turned Their Desperate Rescue Plan Against Them
For days, Liam checked his phone constantly and tried to hide his panic. Then, on Saturday afternoon, he came home early, pale and disheveled, and dropped his briefcase on the floor. “You need to call the bank right now,” he demanded. He claimed a security glitch had frozen his business account and our joint savings, and the broker would foreclose unless the $145,000 arrived by five. He leaned on the marble counter, sweating, still expecting me to solve the emergency he had created.
I turned the bank’s fraud report toward him. “I called on Friday. I confirmed an unauthorized transfer.” His face tightened as I explained that I’d seen Vance’s email, knew about the margin call and Brenda’s second mortgage, and had watched him initiate the wire from my iPad while I showered. The bank had traced the device to our home network. By electronically certifying the transfer, he had forged my authorization. The bank had cancelled the wire, frozen the joint savings, and classified it as suspected wire fraud pending review. “I was going to pay it back,” he insisted. “I just needed a bridge loan. I was protecting our future.” “You were trying to liquidate it,” I replied. “I chose not to pay your debt.”
Brenda arrived less than forty minutes later, furious and frightened. She accused me of letting my husband’s career collapse over “pennies,” insisting I had millions sitting idle and was selfishly hoarding it. She slammed her palm on the counter and reminded me that he was my husband, as if the word made the transfer lawful. I didn’t argue. I took a watermarked trust summary from my work tote and slid it across the counter. Sarah had redacted the sensitive details, leaving the entity name and audited valuation visible.
Brenda’s eyes moved over the page, then stopped. The color drained from her face. Liam leaned in to read the figure: $2.5 billion. I was the primary beneficiary of Apex Holdings, whose blind trust held commercial logistics stock. They had assumed I had a few million; they had no idea how much they’d tried to reach. “If you’d treated me like a wife instead of a bailout,” I told Liam, “you might have shared a future you can’t imagine. Instead, you committed federal wire fraud for pocket change.”
Brenda gripped the counter as her knees weakened. Liam couldn’t speak. Their commercial lot was already heading into foreclosure, and Brenda’s own home was at risk because she had borrowed against it for his venture. I put the trust summary away and told Liam to pack a bag. My attorney would send the divorce filing to his office the next morning. Their desperate plan had not only failed; now they knew exactly what they had thrown away.
Chapter 5: They Lost Everything, While I Finally Reclaimed My Quiet Life
The divorce was handled without courtroom theatrics. Sarah brought in Helen, a sharp family-law attorney, who met Liam and his lawyer across a polished conference table. His side asked for temporary support and a share of the joint funds. Helen slid over the bank’s fraud report and offered a clean separation: each of us would keep the assets and liabilities we brought into the marriage, with no alimony, no division of the Bank of America joint savings, and no claim to my income or the Myers Park lease.
She explained that if Liam refused, we would send the report and digital access logs to federal prosecutors in the Western District of North Carolina. His lawyer read the details, then looked at Liam, who stared at the table. Within fifteen minutes, he signed the agreement. I didn’t press criminal charges myself, but the bank’s fraud record remained attached to his consumer profile. An active fraud flag on his ChexSystems file made it difficult to secure financing, open new credit lines, or maintain his brokerage licenses. The consequences were quiet, but real.
Liam returned on a Saturday to collect his belongings. He packed suits, golf clubs, and his coffee grinder into cheap cardboard boxes, sealing them with strips of tape that screeched through the quiet house. I kept working at the kitchen island. At the front door, he paused as if hoping for a final conversation to give our ten-week marriage some grand, emotional ending, but I didn’t look up. He turned the brass knob and left. That was all the closure we got.
A few weeks later, public records showed that Liam’s commercial lot had been foreclosed and auctioned. Brenda’s second mortgage had consumed the remaining equity in her SouthPark home, and a notice of default was recorded against the property. They had gambled the roof over their heads to reach for my money and lost both. In mid-November, the final dissolution papers arrived in a plain envelope. I opened it with a metal letter opener, read the judge’s signature, and carried my black coffee to the back patio.
Frost silvered the grass, and the oak trees had shed most of their leaves. The house was finally quiet: no whistling in the garage, no Sunday dinners designed to corner me, no husband pretending to care about my day while calculating my balance. I still drove my old Toyota, worked my corporate job, and lived in the same leased house. My trust had never needed to save me; my judgment had. I thought of the blue pen Brenda had pushed toward me on that first morning. I’d returned it to her purse, and with it, refused the future they had tried to sign away for me. Trust, I’d learned, wasn’t blind faith. It was something earned over time—and never granted under pressure. I hadn’t sworn off marriage or stopped believing in people; I had simply learned that a real partner respects boundaries instead of treating them as obstacles.
You Might Also Enjoy
My Mother Called Me Worthless and Locked Me Out of Her Basement—Four Days Earlier, I Had Received $32.4 Million…