“Your brother can use your house better than you!” Dad announced, barging into my honeymoon suite with a notary and a deed bearing my forged signature. He demanded I hand over my Seattle townhouse. I refused. Then my attorney uncovered something terrifying. The deed had already been recorded three days before my wedding. They thought I was a broke software developer. They had no idea I controlled nearly $5 billion.
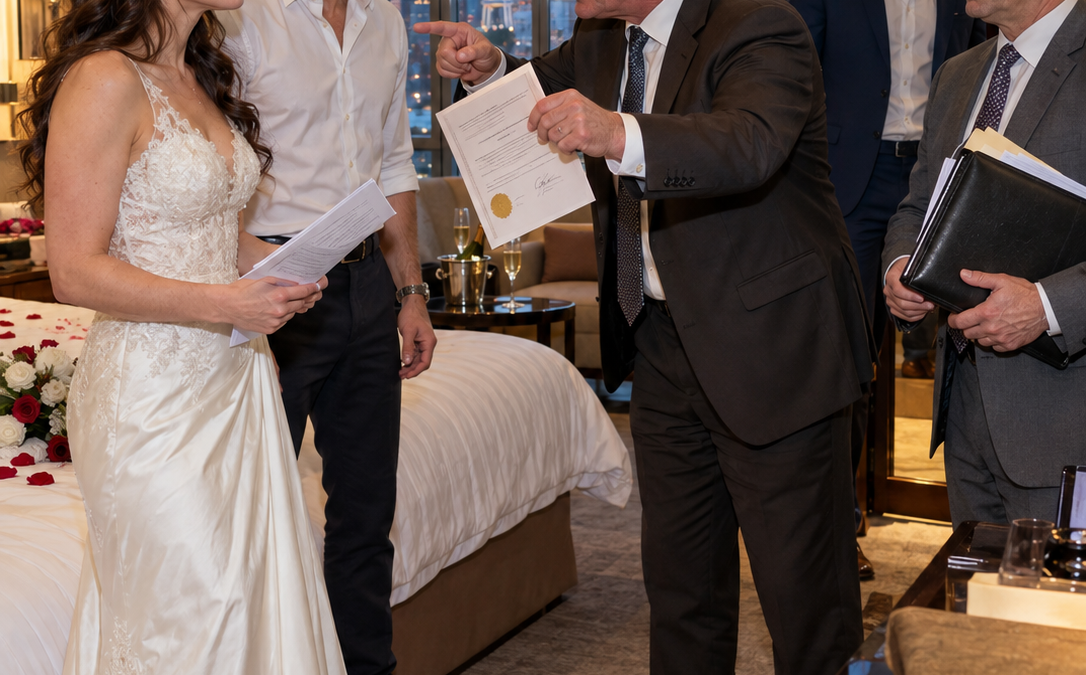
“Your brother can use your house better than you!” Dad announced, barging into my honeymoon suite with a notary and a deed bearing my forged signature. He demanded I hand over my Seattle townhouse. I refused. Then my attorney uncovered something terrifying. The deed had already been recorded three days before my wedding. They thought I was a broke software developer. They had no idea I controlled nearly $5 billion.
PART 1/5 — My Father Arrived After Our Wedding With My Forged Signature
At 8:15 the morning after my wedding, I opened our hotel-room door wearing a bathrobe and holding a coffee mug. My father looked past me as though he owned the place.
“We need ten minutes, Daniel,” Russell Ward said.
Behind him stood a thin man in a brown suit with a leather portfolio and a notary-public badge. Dad didn’t introduce him. He headed straight for the table by the window, moved the flowers I’d ordered for Emily, and spread out several documents.
“Your brother’s putting the family finances in order,” he said. “Now that you’re married, we need to make sure everything’s protected.”
I had learned to distrust the phrase the family whenever Dad used it in a sentence about money.
He pointed to a signature line on a document titled Asset Management Authorization. It would give my older brother, Carter, broad authority to act on my behalf in financial matters. Underneath it sat a quitclaim deed for my townhouse in West Seattle, naming Carter’s property company as the recipient.
The deed already carried my name in ink.
“That’s not my signature,” I said.
Dad barely glanced at it. “The attorney prepared everything ahead of time. This is just the confirmation page.”
“Then why is that page notarized?”
The man by the door cleared his throat. “I’m here to witness any documents signed today. I wasn’t involved in that one.”
Dad shot him a look that shut him up.
Emily stirred under the covers. I lowered my voice. “Who gave you permission to transfer my house?”
“Nobody’s transferring anything away from you. Carter can use the equity more efficiently than you can. You’ll still live there.”
“I’m not signing.”
Dad blinked. He’d imagined I’d apologize for inconveniencing him, pick up a pen, and ask where to write my name.
“Don’t embarrass me in front of a professional,” he said.
I gathered the documents. “Then don’t bring a professional to my honeymoon. My attorney will review these.”
He reached for the folder, thought better of it, and straightened his tie. “Carter has people waiting.”
When the door closed, I noticed coffee had spilled onto my wrist. My hand was shaking.
“Daniel?” Emily sat upright. “Why was your dad talking about our house?”
I told her he wanted Carter to manage some property paperwork. It wasn’t exactly a lie, which made it a particularly bad answer.
We’d been married in a greenhouse overlooking Puget Sound. Emily, a pediatric nurse, had wanted twenty guests, good food, and no seating chart. Dad insisted on inviting his former business partners. Carter offered to “upgrade” the reception. I paid the extra bill because arguing had seemed exhausting, and because I could afford it.
The truth was I could afford almost anything. Seven years earlier, I’d helped build a company that licensed encryption systems to hospitals and logistics firms. I worked under my cofounder’s public-facing leadership, and my ownership stayed out of sight. After a private acquisition and years of investments, the holdings in a trust established for me were valued at just under $5 billion. Most of that wasn’t spendable cash. It was equity and investments, managed by people whose job was to tell me when an idea was stupid.
My family knew me as the quiet son who wrote software and drove a ten-year-old Subaru. I hadn’t corrected them. For years, my father had called my job “computer stuff” while introducing Carter as the future of the Ward family.
Carter was thirty-six, handsome, and good at persuading other people that confidence was the same as competence. Dad paid for his tuition, his first office, and the down payment on a condo. When my car broke down in college, Dad suggested taking the bus because “independence builds character.”
I did. I worked midnight shifts at a data center until I could afford repairs.
I hadn’t hidden the money to teach anyone a lesson. Privacy was comfortable, and once the number became absurdly large, sharing it felt less like telling someone good news and more like handing over control of every conversation we’d ever have.
Emily knew I’d earned substantial money from a company sale. She didn’t know the scale. I had persuaded myself that telling her after the wedding would prove she loved me for me. Watching her face that morning, I began to understand how unfair that reasoning was to her.
“Is the house in danger?” she asked.
“I don’t think so. But I need to check.”
“Then let’s check together.”
Instead, I called Dana Holt, the attorney who handled my personal affairs, and asked her to look at the papers while Emily packed. I told myself I was sparing my new wife a messy family fight. Really, I was delaying a conversation I feared.
Our honeymoon was twelve days on Maui. Dad called twice before our plane left Seattle. Carter sent a message during our first dinner: Dad’s trying to help you. Don’t make this weird. The next morning: We need those documents before the fifteenth.
I put my phone facedown beside a plate of pineapple pancakes. Emily watched me do it.
“Your brother again?”
“Yeah.”
“You look like you’re waiting for a diagnosis.”
That afternoon I told her about the signature. She sat on the hotel balcony for a long time before saying, “He used your name on a deed? That’s not paperwork, Daniel.”
She was right. I sent Dana clear photographs of every page, including the notary stamp and recording reference typed in the corner. Dana replied that she’d check the county records and contact a real-estate attorney.
For the first time in years, I wished Carter would call just to ask how I was doing.
When we landed back in Seattle, a message from Dana was waiting. The deed wasn’t merely prepared. It had been recorded with King County three days before our wedding.
Someone had already put my house in my brother’s company’s name, at least on paper, and was counting on me not noticing until it was too late.
PART 2/5 — The County Records Showed Why My Brother Needed My House
Dana met Emily and me in her downtown office the following Tuesday. She had a printed copy of the recorded deed, a yellow legal pad, and the expression she usually reserved for particularly bad contracts.
“The recorder doesn’t verify that a signature is genuine,” she explained. “It records a document that meets filing requirements. Undoing this may require a court order.”
The deed claimed I’d signed it on a Thursday evening. Emily checked our shared calendar. We’d been having dinner with her parents. She had photographs, including one timestamped less than an hour before the supposed notarization. It wasn’t proof of where I’d been every minute, but it was a start.
Dana had already asked a title specialist to flag the dispute. She told me to file a police report, notify my homeowner’s insurer, and preserve the original packet. We also sent Carter’s company formal notice that I contested the deed and would challenge any attempted sale or borrowing against the property.
Then Dana turned her laptop toward us.
Carter’s company, Cascade Retail Partners, had acquired a commercial parcel outside Tacoma for a shopping development. Public filings showed a substantial loan secured by the land. A notice of default had been recorded weeks earlier. Another filing showed Dad had taken a second mortgage on the Bellevue house where we’d grown up.
“Your father put his own home on the line,” Dana said. “I can’t tell you the full amount they owe from these records.”
Carter supplied the missing piece himself that evening.
He called while I was unloading groceries. “I’m not asking you to give me money,” he said. “It’s a ninety-day bridge. Eight hundred and fifty thousand. I’ll pay interest.”
I put the milk on the counter. “That’s a very specific number for someone who was asking me to sign routine paperwork.”
“The Tacoma lender wants additional cash before the fifteenth. If I don’t cover it, they move against the project. Dad’s collateral gets dragged in too.”
“So you signed my name to a deed?”
“Dad had a lawyer work something up. Don’t turn this into a criminal accusation.”
“Did you sign my name?”
“We can sort that out after the financing closes.”
He hung up.
That night Emily and I ate reheated pasta at the kitchen island. She kept turning her wedding ring around her finger.
“Your dad didn’t suddenly become interested in our marriage,” she said. “He became interested in the calendar.”
I thought about the rushed wedding, the new warmth, the insistence on involving Carter in everything. The commercial lender’s deadline had been approaching the entire time.
Then Dana forwarded an unexpected email she’d received from the lender’s title company. Attached was a financing consent form bearing the imitation of my signature.
I stared at it until Emily gently took the phone from my hand. Someone had told the lender I was already on board. This wasn’t only about what Carter might do with my money. He was making promises to a bank in my name.
PART 3/5 — I Told My Wife the Truth Before We Locked Everything Down
The next morning, I told Emily about the trust.
We sat at the same kitchen island where we’d eaten pasta. I showed her the latest audited statement, explained which holdings were illiquid, and described the restrictions I’d put in place years earlier to keep the trust separate from my daily banking.
She read the valuation twice. “Five billion?”
“Approximately. It changes with the market.”
She pushed the paper back. “I know how numbers work, Daniel. Why didn’t you trust me with this one?”
I started to say I’d wanted her to love me without the money. She held up a hand.
“You made that decision for both of us. We talked about student loans, having kids, whether we’d ever afford a bigger house. I thought we were making plans with the same information.”
I didn’t have a defense that sounded good spoken aloud. I apologized without trying to make the apology useful. She asked for space, then took a long walk by herself.
When she returned, she said, “I’m angry. I’m also not letting your father steal our home. Both things can be true.”
We spent the afternoon with Dana and the trust’s financial adviser. They confirmed that the trust couldn’t simply be reached through the deed or Carter’s authorization form, but my ordinary accounts and property still needed protection. We froze my credit with all three bureaus, notified the bank of a possible impersonation attempt, replaced shared-device passwords, and disabled saved banking credentials.
Carter had once helped me move, carrying boxes of bank statements and tax documents. I couldn’t tell whether he’d copied an account number or photographed a statement, but Dana said we needed facts, not guesses.
The bank added extra verification for high-value transfers and alerts to my phone. We also asked the fraud department to note that any power of attorney presented by a relative was disputed. Nobody promised those measures were perfect.
Emily prepared a timeline of the days around the supposed deed signing, matching photographs, receipts, and messages. I watched her work and realized I’d been so busy trying to spare her trouble that I’d underestimated how much stronger we were when she could actually help. Later, she said she still wanted us to talk about the money without an attorney in the room. I agreed.
That Thursday, Carter came by with takeout and a strained apology. Emily wanted him gone. I let him speak on the porch, where our doorbell camera recorded him saying the deed was “just security” and he’d fix it once the bridge loan cleared.
I said he needed to work through Dana. He asked to come in and use our bathroom. I said no.
An hour later, my phone buzzed with a bank alert. Someone had requested an $850,000 wire from my personal savings to an account associated with Cascade Retail Partners. The transaction was pending further verification.
I had changed my passwords. Apparently, Carter hadn’t needed them. Someone was trying to use the paperwork itself as a key.
PART 4/5 — An Unauthorized Transfer Forced My Father to Explain the Forgery
The bank’s fraud investigator called Friday morning. I confirmed I hadn’t authorized the wire, and she canceled the pending transfer. She couldn’t tell me who’d initiated it or promise an arrest. She could open an investigation, preserve the access records, and advise me to make another police report.
Dana spoke with the bank’s fraud team. The request had come through paperwork submitted to a branch by someone claiming to act under a power of attorney. A scanned version included a signature that resembled the one on the forged deed. I felt sick thinking about how easily Carter might have moved my ordinary savings if the bank hadn’t called to verify the request.
When Carter called, I didn’t tell him what we’d learned. I said every further conversation had to go through my attorney.
By Saturday, Dad was on my porch, pounding hard enough to rattle the glass.
“You’re destroying your brother’s business,” he said when I opened the door.
Emily stood behind me. “He tried to take money from our account.”
Dad’s eyes flicked to her. “That’s a family misunderstanding.”
“Then why is there a recorded deed with a signature I didn’t write?” I asked.
He exhaled. “Carter was going to lose the Tacoma property. I guaranteed part of his loan. The house in Bellevue could be next. We needed temporary collateral.”
“You needed my consent.”
“You would’ve said no.”
There it was. Not a confession to every detail, but enough to tell me that the choice had been deliberate.
“You knew it wasn’t my signature,” I said.
He looked at the floorboards. “I knew Carter was handling the documents. I didn’t ask every question I should’ve.”
“You brought a notary to my hotel room to make me approve something I’d never agreed to.”
“I was trying to save the house,” he said. For a moment his voice sounded older than I’d ever heard it. Then he straightened his shoulders, ready to turn necessity into an excuse again.
Dad held out his hand. “Let me explain this without your wife standing here.”
“She’s my wife. She stays.”
“I could help with the debt,” I said. “I won’t help by pretending fraud is normal.”
“With what? Your little savings account?”
But I was tired of being treated as a child who couldn’t understand the stakes. I showed him the cover page of the trust statement Emily and I had reviewed, with account identifiers hidden.
Dad leaned closer, then glanced at me as if I’d handed him a foreign language. “Is this real?”
“Yes. But it isn’t yours.”
The number at the bottom was just under $5 billion.
He sat down on the porch step. A minute earlier he’d been furious about the money I supposedly wouldn’t lend. Now he was staring at a fortune he’d never known existed.
“Then you can save us,” he whispered.
Emily reached for my hand. I told him he would need to leave, and that Dana would handle the rest. For once, he went without arguing.
PART 5/5 — The House Was Finally Ours Again but Trust Took Longer
The recorded deed didn’t disappear because I reported it. It took sworn statements, signature comparisons, records requests, and a civil action challenging the transfer. The lender that had been considering Carter’s collateral backed away once it received formal notice of the dispute. Months later, after Carter’s company signed documents relinquishing its claim, the court approved an order clearing the title.
The bank investigated the unauthorized transfer separately. Carter’s attorney disputed intent, describing it as a loan request made under a misunderstanding. The submitted authorization and the attempted transfer amount didn’t make that explanation easy. I cooperated with investigators, but I didn’t get to decide whether prosecutors brought charges. For a while, I had to learn to live without that answer. It was frustrating to give my account of what happened and then step aside, but Dana reminded me that building a reliable record mattered more than getting a satisfying phone call.
Carter lost the Tacoma project when his lender enforced its rights under the loan agreement. Dad sold the Bellevue house rather than wait for foreclosure. After paying secured debts and closing costs, he moved into a small rental. I learned this from a public property listing and one short letter from his lawyer. I drove past the house once while dropping off a package nearby. The white columns were still there, but the yard sign carried another family’s name. I kept driving.
The letter asked whether I’d consider helping with living expenses. I sent it to Dana. We arranged no payment and no conversation. Dad had spent decades telling me I needed to stand on my own feet. I figured he’d recognize the advice.
Emily and I had harder work to do. The week after my disclosure, she asked us to meet with an independent financial planner and a marriage counselor. She wanted clear answers about our money, our future, and why I’d felt entitled to test her without her knowing.
She was right. The wealth wasn’t a prize I could reveal when it suited a dramatic moment. It was part of the life she’d agreed to share, and I’d hidden it behind a story about protecting love.
We opened a joint account for household expenses, worked through estate-planning documents, and kept talking even when it would’ve been easier to argue about someone else’s betrayal. I told her things before they became emergencies. She told me when I started retreating into silence.
We started planning our first anniversary: a small dinner at home with the friends who’d helped set up our wedding chairs.
Six months after the wedding, we were back in the townhouse. Emily was making coffee before an early hospital shift when someone knocked at the front door. For one ugly second, I was back in that hotel bathrobe, looking at Dad’s folder.
It was a neighbor returning a borrowed ladder. I thanked him and shut the door.
“Everything okay?” Emily called from the kitchen.
“Just the neighbor,” I said, reaching for the coffee Emily had poured.
THE END